Question 6May/Jun 20269706/111 mark
Which statements describe limitations of reconciliation and verification procedures in accounting?

Show answer
BCorrect answer
Cambridge 9706, Paper 1 & 2. 1,558 questions, 2020 to 2026.
Pages reproduced from the original Cambridge question papers and mark schemes. Tables, ruled accounts and answer templates are cropped images, not retyped — shown on a white card so they stay readable in dark mode. Paper 2 questions with parts in more than one topic are filed whole under every topic they touch; parts outside the chosen topics are dimmed. Click any image to enlarge it. Mark schemes are hidden until you choose to reveal them.
Sales ledger and purchases ledger control accounts: preparing them, reconciling them with the ledgers, and set-offs.
67 past paper questions on this topic since 2020, across 13 exam sessions.
| Year | Paper 1 | Paper 2 | Total | Chart |
|---|---|---|---|---|
| 2026 | 13 | 0 | 13 | |
| 2025 | 12 | 2 | 14 | |
| 2024 | 6 | 2 | 8 | |
| 2023 | 11 | 1 | 12 | |
| 2022 | 9 | 0 | 9 | |
| 2021 | 4 | 2 | 6 | |
| 2020 | 4 | 1 | 5 |
The whole topic on one page, with answers and mark schemes. Printing this page prints just this list.
Which statements describe limitations of reconciliation and verification procedures in accounting?
BCorrect answer
A business has discovered several errors in its sales ledger. All the accounts in the other ledgers have been entered correctly. The business does not maintain control accounts. Which error will not affect the agreement of the trial balance? A A sale to Clark of $2000 was debited to Clarkson’s account. B A sale to Garcia of $100 was entered in Garcia’s account as $1000. C A sale to Wong of $4700 was omitted from Wong’s account. D A sales return of $1200 was debited to Khan’s account.
ACorrect answer
What is not a purpose of control accounts?
BCorrect answer
A business maintains control accounts as a part of its double entry system. A sales ledger control account has been prepared from the following details.
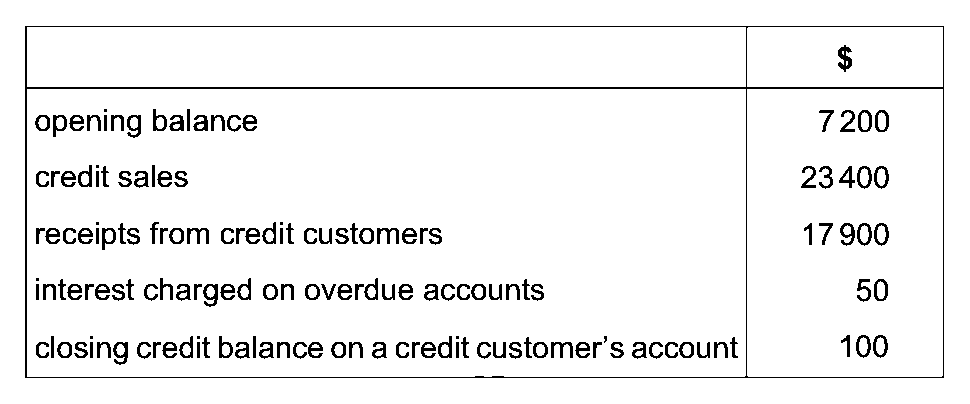
What should be the total of debit balances in the sales ledger?

DCorrect answer
What are benefits of using verification and reconciliation procedures?
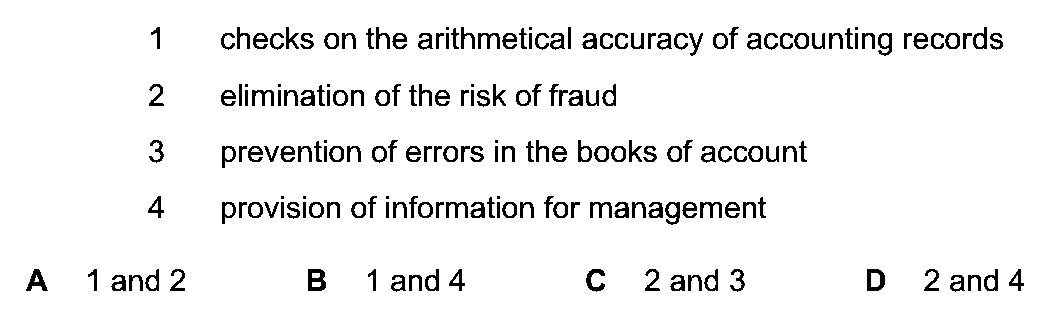
BCorrect answer
Which item is recorded on the debit side of a sales ledger control account?
ACorrect answer
At the end of a financial period, the total of the balances on the individual accounts in the purchases ledger was $39500. This did not agree with the balance on the purchases ledger control account. The control account is part of the double entry system. The following errors were then discovered.
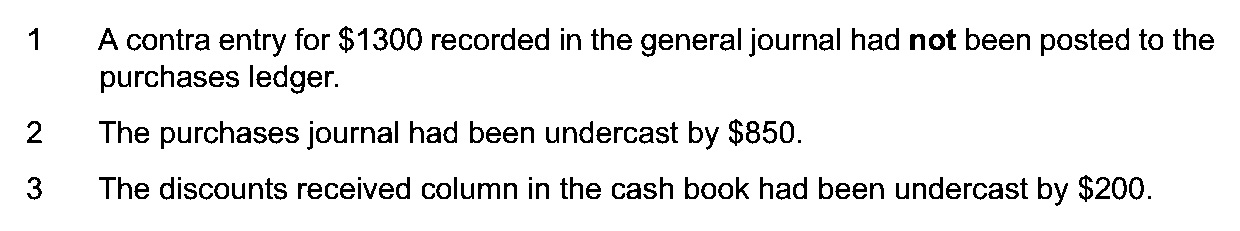
After the relevant corrections were made, the total of balances in the purchases ledger agreed with the balance on the purchases ledger control account. What was the balance on the purchases ledger control account before making the corrections?

ACorrect answer
Which statements describe limitations of reconciliation and verification procedures in accounting?

BCorrect answer
A business has discovered several errors in its sales ledger. All the accounts in the other ledgers have been entered correctly. The business does not maintain control accounts. Which error will not affect the agreement of the trial balance? A A sale to Clark of $2000 was debited to Clarkson’s account. B A sale to Garcia of $100 was entered in Garcia’s account as $1000. C A sale to Wong of $4700 was omitted from Wong’s account. D A sales return of $1200 was debited to Khan’s account.
ACorrect answer
What is not a purpose of control accounts?
BCorrect answer
A business maintains control accounts as a part of its double entry system. A sales ledger control account has been prepared from the following details.
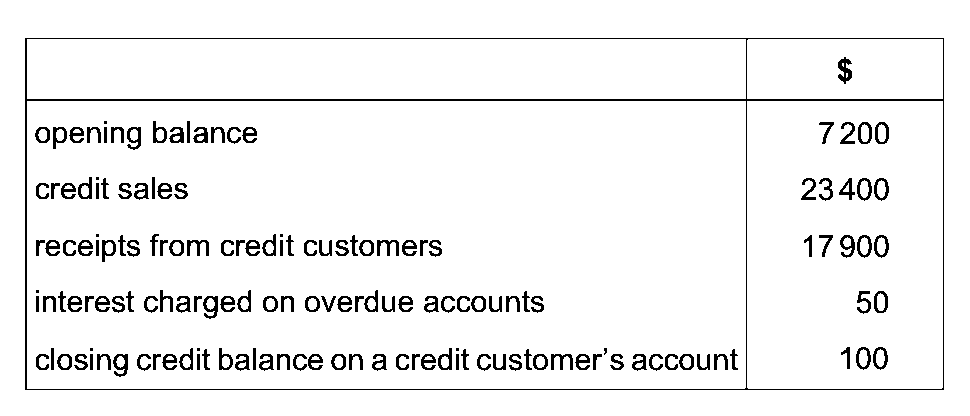
What should be the total of debit balances in the sales ledger?

DCorrect answer
What would not appear in a sales ledger control account?
ACorrect answer
A purchases ledger control account has a balance of $20000. This does not agree with the total of the individual purchases ledger balances. Control accounts are maintained as part of the double entry system. The following items were discovered.

What is the corrected purchases ledger control account balance?

BCorrect answer
A business makes all sales on credit. Its sales ledger control account had a balance of $20 000 at the end of July. During August, the following transactions were recorded.
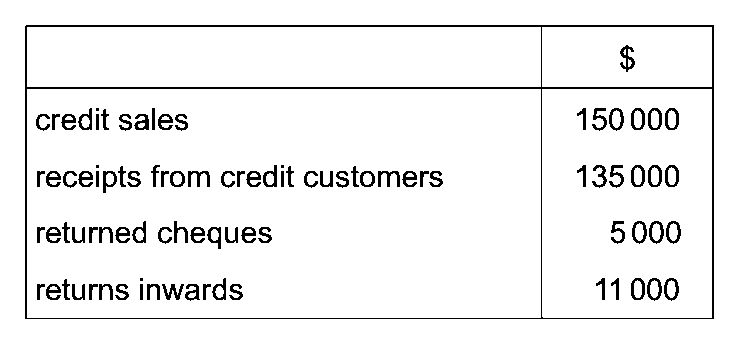
What was the sales ledger control account balance at the end of August?

CCorrect answer
A business maintains control accounts as a part of its double entry system. The balance of the purchases ledger control account is $8232. However, this does not agree with the total of balances in the purchases ledger. The following account for the difference. 1 An entry in the purchases returns journal for $72 has been posted to the credit side of the individual trade payable’s account in the purchases ledger. 2 An entry for discounts received in the cash book for $54 has been debited to the individual trade payable’s account in the purchases ledger as $45. What is the total of balances in the purchases ledger before these errors are corrected?

DCorrect answer
A sales ledger control account included the following entries:
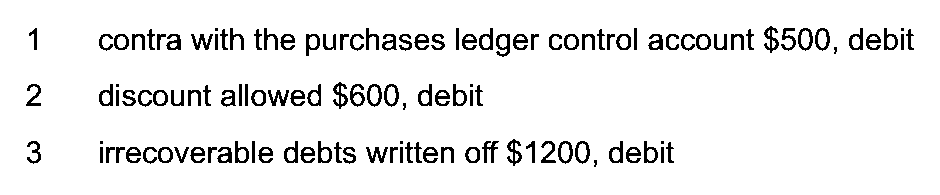
Which entries must be corrected?

ACorrect answer
A business maintains control accounts as a part of the double entry system. At 31 December, the balance of $23 400 in the sales ledger control account did not agree with the total of the individual sales ledger balances. The following errors were discovered.
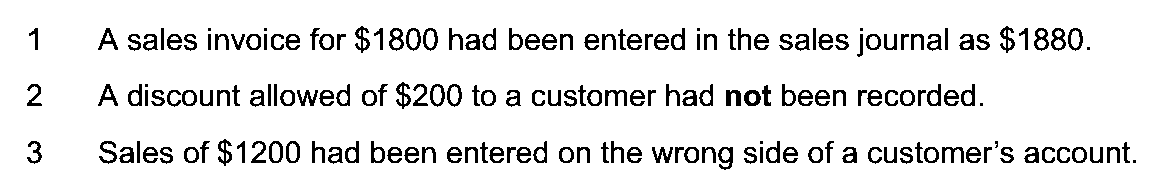
What is the correct balance in the sales ledger control account at 31 December?

ACorrect answer
Which item should be recorded as a debit entry in a sales ledger control account?
BCorrect answer
Some errors were made when preparing a purchases ledger control account. The incorrect balance was $15830. The following errors were discovered. 1 Refunds of $270, from credit suppliers, had been omitted from the control account. 2 The total of discounts received of $480 had been posted to the wrong side of the control account. What was the corrected balance of the purchases ledger control account?

CCorrect answer
Why is a sales ledger control account used?

DCorrect answer
A bookkeeper is given the task of reconciling the sales ledger control account with balances in the sales ledger at the end of each month. The sales ledger control account showed a debit balance of $26000 before the bookkeeper discovered the following:
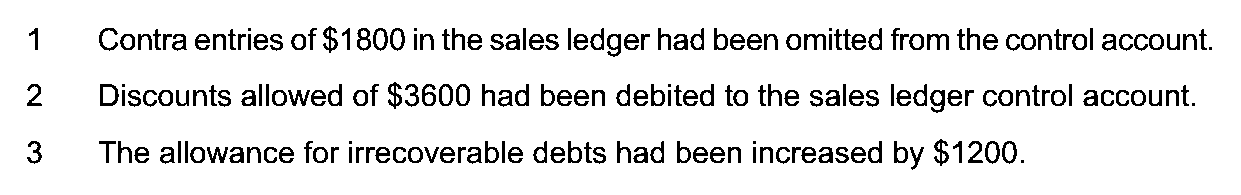
What is the correct figure for trade receivables at the end of the month?

BCorrect answer
Which item should be recorded as a debit entry in a sales ledger control account?
BCorrect answer
Some errors were made when preparing a purchases ledger control account. The incorrect balance was $15830. The following errors were discovered. 1 Refunds of $270, from credit suppliers, had been omitted from the control account. 2 The total of discounts received of $480 had been posted to the wrong side of the control account. What was the corrected balance of the purchases ledger control account?

CCorrect answer
Which statement is not correct about the benefit to a business of maintaining control accounts?
ACorrect answer
A business maintains control accounts as part of the double entry. At the end of a financial period, the sales ledger control account balance of $64 200 did not agree with the total of the individual sales ledger balances of the business. The following errors were discovered. 1 An irrecoverable debt of $800, entered in the sales ledger control account, was omitted from the trade receivable account. 2 Discounts allowed of $950 were entered in the sales ledger accounts but were entered as $590 in the cash book. 3 A contra of $4100 between accounts in the sales and purchases ledgers was reversed in the control accounts. There were no further errors. What was the total of the trade receivables at the end of the period after adjustments?

BCorrect answer
Reza owns a large retail business. As the business has many credit customers and credit suppliers, she was advised to maintain purchases ledger and sales ledger control accounts.
(a) Explain two benefits of maintaining control accounts. [4 marks]
(b) Prepare the purchases ledger control account for January 2025. [6 marks]
Reza decides to maintain control accounts as a part of the double entry system. On 1 January 2025, the balance of the purchases ledger control agreed with the total of balances in the purchases ledger of $23 420. The following is a summary of transactions for January 2025.


(c)(i) Calculate an amended figure for each of the following: sales ledger total of balances [2 marks]
On 31 January 2025, the total of the balances in the sales ledger was $17 180. However, the balance on the sales ledger control account was different. The following errors have been discovered which account for this difference. 1 The balance of the sales ledger control account had been miscalculated. The total of the debit entries was $82 490, and the total of the credit entries was $65 550. 2 The total of the discounts allowed column in the cash book had been undercast by $90. 3 A credit note issued to a credit customer for $120 had been correctly entered in the book of prime entry but had been debited to the account of the customer as $210.
(c)(ii) Calculate an amended figure for each of the following: sales ledger control account balance. [3 marks]
On 31 January 2025, the total of the balances in the sales ledger was $17 180. However, the balance on the sales ledger control account was different. The following errors have been discovered which account for this difference. 1 The balance of the sales ledger control account had been miscalculated. The total of the debit entries was $82 490, and the total of the credit entries was $65 550. 2 The total of the discounts allowed column in the cash book had been undercast by $90. 3 A credit note issued to a credit customer for $120 had been correctly entered in the book of prime entry but had been debited to the account of the customer as $210.
(a)
Provide an arithmetical check on the accuracy of the purchases and sales ledgers (1), enabling any errors to be discovered quickly (1). Assists in the preparation of trial balances and financial statements (1), as totals of trade payables and trade receivables can be found quickly (1). May help deter fraudulent activity (1) as they provide independent verification/division of duties (1). Max 2 benefits x 2 marks (1 mark for identifying + 1 mark for development ) Accept other valid responses
(b)
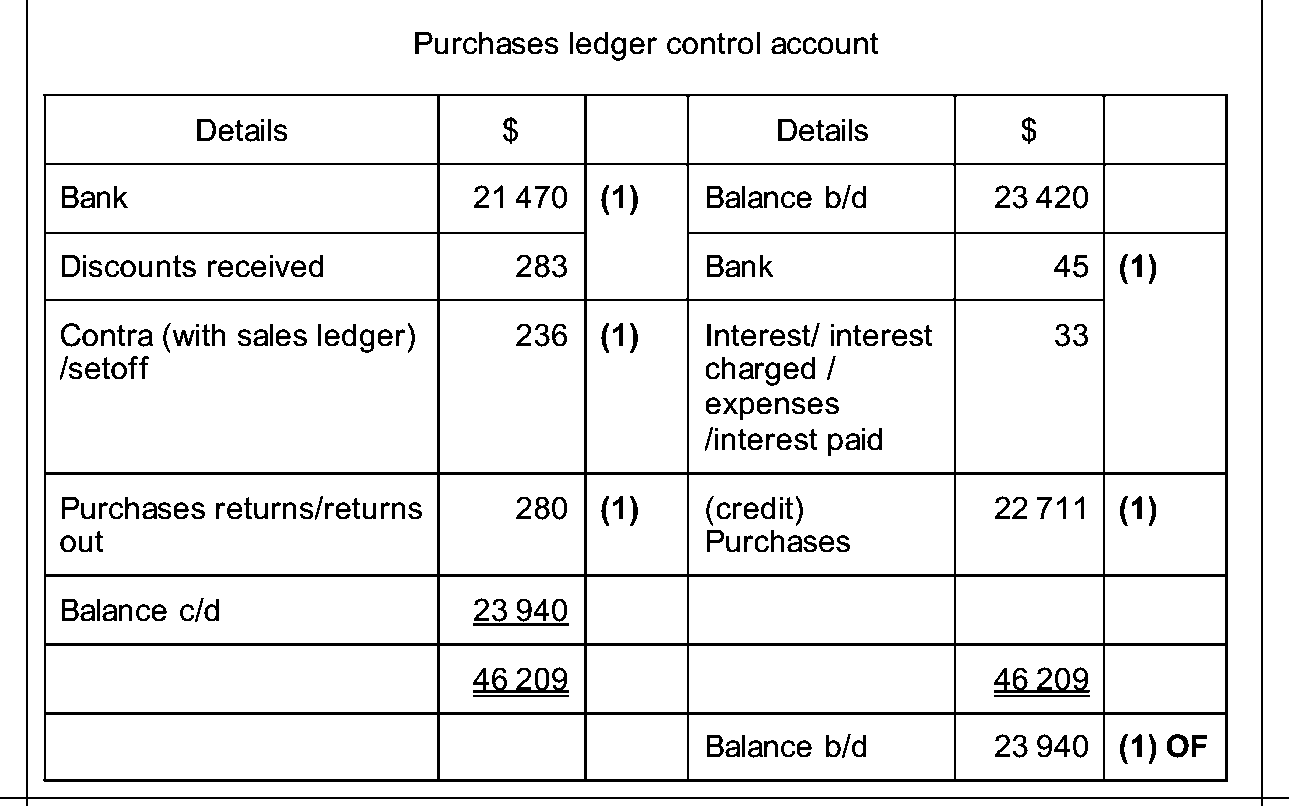
(c)(i)

(c)(ii)
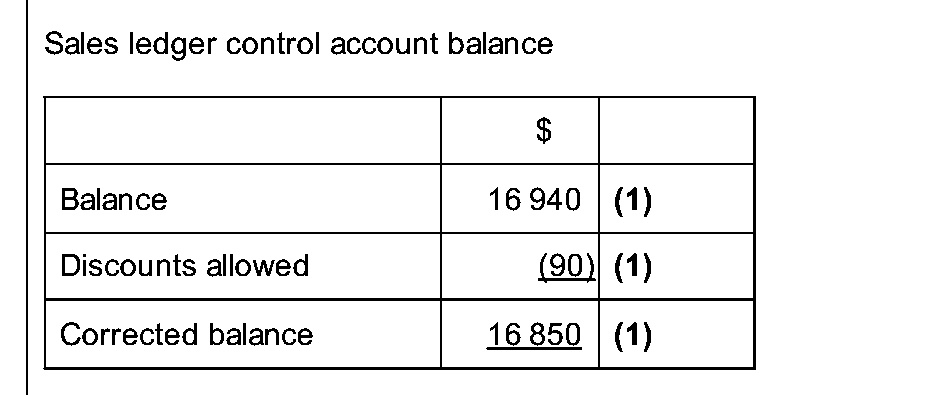
Moe runs a trading business and maintains control accounts as a part of the double entry. The following information is available for the month of November 2024.
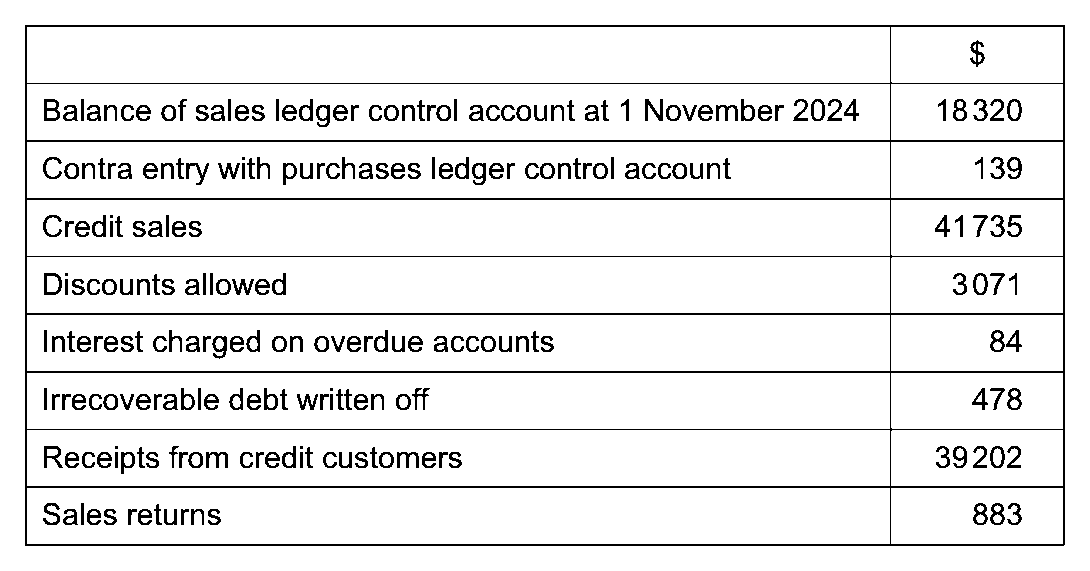
(a) Prepare the sales ledger control account for November 2024. Dates are not required. [5 marks]

(b)(i) Calculate the corrected figure for: the total of balances in the sales ledger [3 marks]
On 31 December 2024, the following information was available.

The following errors were discovered, which accounted for the difference. 1 The balance of a credit customer’s ledger account had been overstated by $189. 2 The total of the sales returns journal, $210, had been posted to the debit side of the control account as $120.
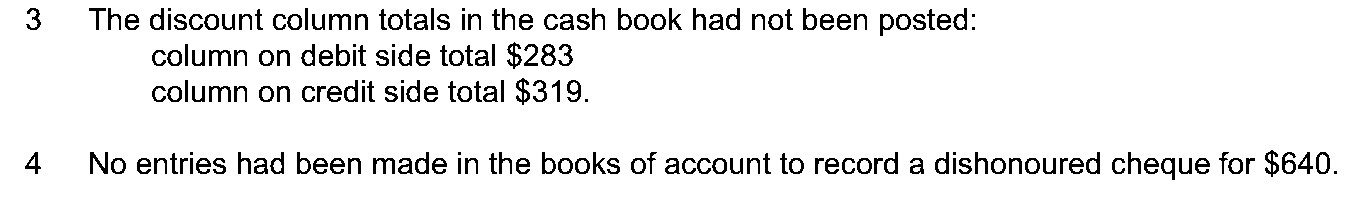
5 An irrecoverable debt of $892 had been recorded correctly in the customer’s ledger account but had been debited to the sales ledger control account as $298.

(b)(ii) Calculate the corrected figure for: the sales ledger control account balance [5 marks]
On 31 December 2024, the following information was available.
The following errors were discovered, which accounted for the difference. 1 The balance of a credit customer’s ledger account had been overstated by $189. 2 The total of the sales returns journal, $210, had been posted to the debit side of the control account as $120.
5 An irrecoverable debt of $892 had been recorded correctly in the customer’s ledger account but had been debited to the sales ledger control account as $298.

(c) State two benefits of preparing control accounts. [2 marks]
(a)

(b)(i)

(b)(ii)

(c)
Check the arithmetical accuracy of the double entry OR ledger accounts (1) Helps to locate errors or indicates errors (1) Helps to prevent/reduce fraud (1) Provides easily accessible information for management (1) Provides information for entry in financial statements OR finds totals for trade receivables OR finds totals for trade payables (1) Improves internal control (1) Max 2 Accept other valid responses
🔒 Unlock every Control accounts question from 2020–2024
All 40 come with their mark schemes, answers and case studies, and appear in the practice tool above once you’re signed in. It’s free.
Questions and mark schemes are from past Cambridge papers and are reproduced for revision. Topical Vault is an independent revision resource, not affiliated with or endorsed by Cambridge Assessment International Education.
Each topic opens this practice tool with only that topic’s questions, plus how often it comes up and every question on it in one list.