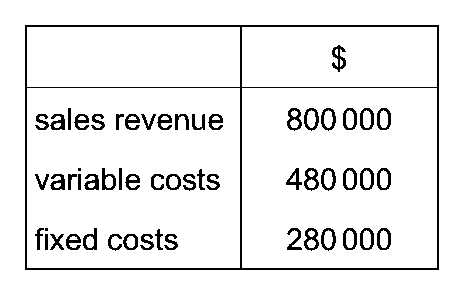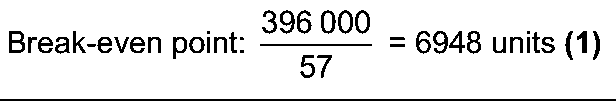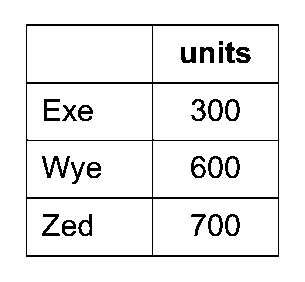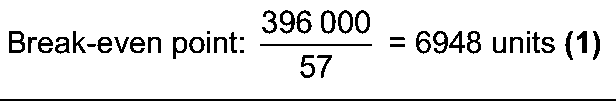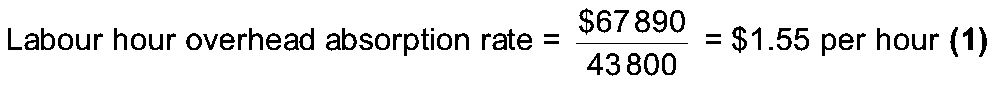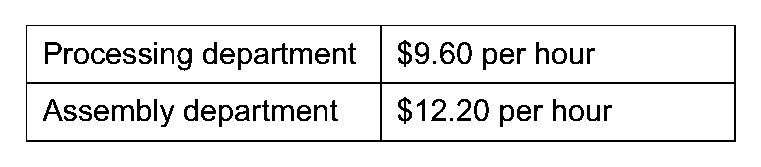Cambridge 9706, Paper 1 & 2. 1,558 questions, 2020 to 2026.
Topic
Year
Pages reproduced from the original Cambridge question papers and mark schemes. Tables,
ruled accounts and answer templates are cropped images, not retyped — shown on a white card so
they stay readable in dark mode. Paper 2 questions with parts in more than one topic are filed whole
under every topic they touch; parts outside the chosen topics are dimmed. Click any image to enlarge
it. Mark schemes are hidden until you choose to reveal them.
About Marginal costing
Marginal costing: contribution, break-even, margin of safety, make-or-buy and other decisions, and comparing marginal with absorption costing.
191 past paper questions on this topic since 2020, across 13 exam sessions.
How often it comes up
Year
Paper 1
Paper 2
Total
Chart
2026
13
3
16
2025
34
7
41
2024
34
6
40
2023
25
5
30
2022
25
5
30
2021
13
3
16
2020
15
3
18
Every 2025–2026 question on Marginal costing
The whole topic on one page, with answers and mark schemes. Printing this page prints just this list.
Paper 1 · Multiple choice (47)
Question 28May/Jun 20269706/111 mark
A business budgeted to produce and sell 10000 units to achieve a profit of $40000. It has a budgeted selling price of $38 per unit and total fixed overheads of $90000. What is the budgeted variable cost per unit?
Show answer
ACorrect answer
Question 29May/Jun 20269706/111 mark
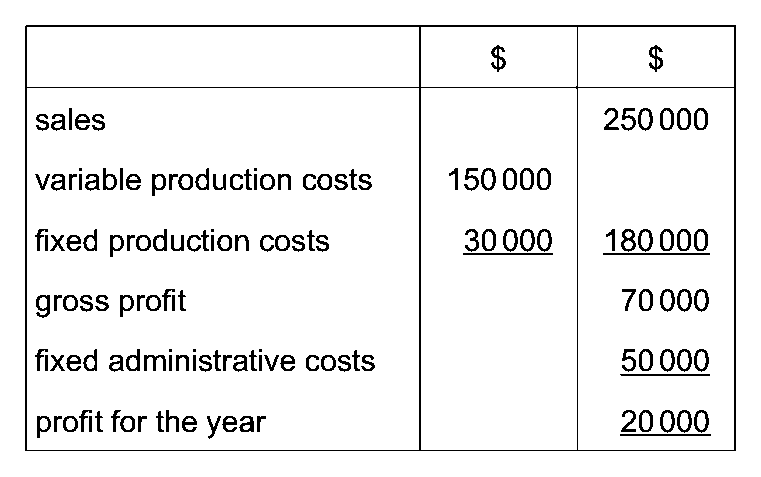
Y Limited produced 100 units in a month. The costs incurred in the month were as follows:
What is the value of one unit of inventory if marginal costing is applied?
Show answer
ACorrect answer
Question 30May/Jun 20269706/111 mark
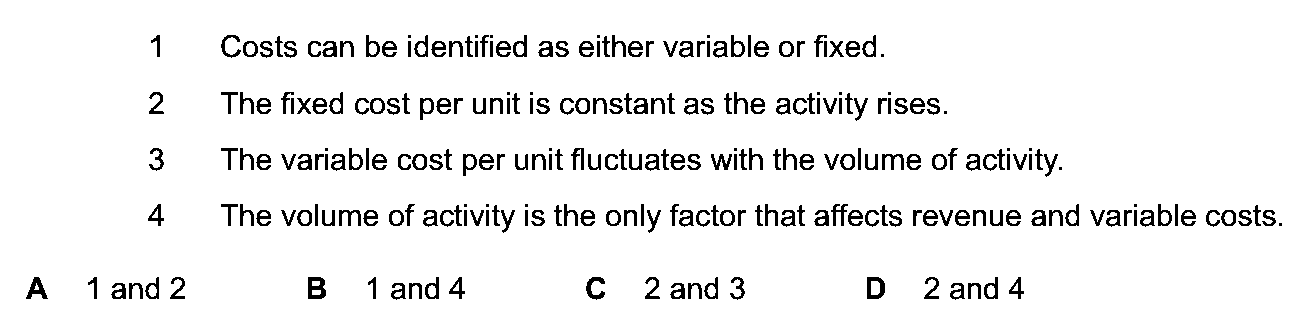
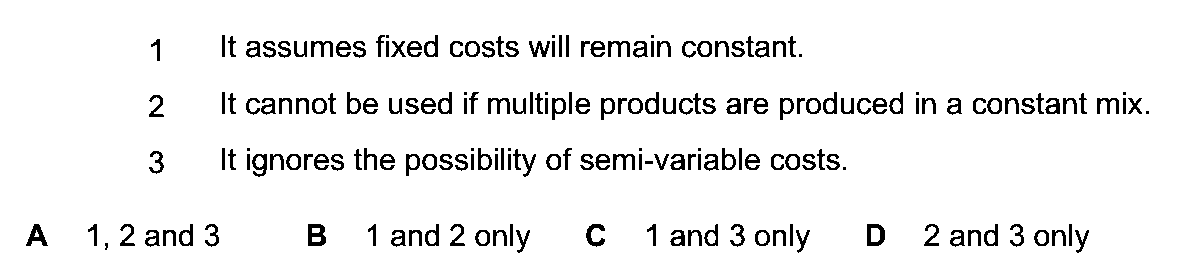
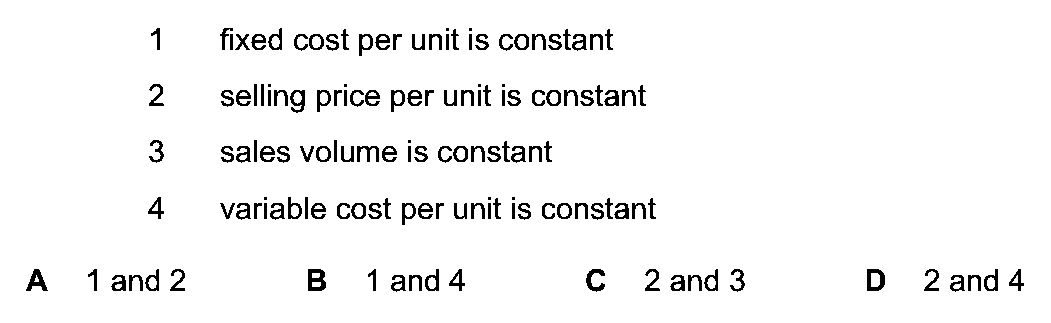
What are the assumptions of cost–volume–profit analysis?
Show answer
BCorrect answer
Question 25May/Jun 20269706/121 mark
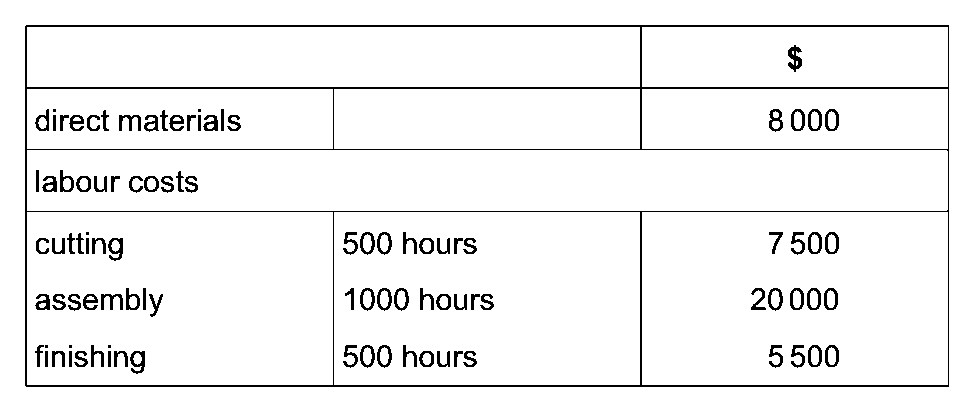
A business manufactures a batch of 1000 tables for a furniture store. The costs of a batch are as follows:
Fixed overheads are absorbed at 20% of labour costs. What is the cost per table?
Show answer
BCorrect answer
Question 28May/Jun 20269706/121 mark
Which statement is not an assumption in break-even analysis?
AAll units produced are sold.
BCosts can only be divided into fixed costs and variable costs.
CTotal revenue and total costs are represented by straight lines.
DUnit selling price, unit variable costs and unit fixed costs remain constant.
Show answer
DCorrect answer
Question 30May/Jun 20269706/121 mark
Which statement about cost−volume−profit analysis is correct?
AIt can help to achieve a reduction in fixed costs.
BIt can only be shown in the form of a graph.
CIt is useful for long-term decision making.
DIt is useful for short-term decision making.
Show answer
DCorrect answer
Question 28May/Jun 20269706/131 mark
A business budgeted to produce and sell 10000 units to achieve a profit of $40000. It has a budgeted selling price of $38 per unit and total fixed overheads of $90000. What is the budgeted variable cost per unit?
Show answer
ACorrect answer
Question 29May/Jun 20269706/131 mark
Y Limited produced 100 units in a month. The costs incurred in the month were as follows:
What is the value of one unit of inventory if marginal costing is applied?
Show answer
ACorrect answer
Question 30May/Jun 20269706/131 mark
What are the assumptions of cost–volume–profit analysis?
Show answer
BCorrect answer
Question 23Feb/Mar 20269706/121 mark
The diagram illustrates the total cost behaviour of a telephone invoice.
$
Which term best describes the behaviour of this cost?
Afixed
Bsemi-variable
Cstepped
Dvariable
Show answer
BCorrect answer
Question 28Feb/Mar 20269706/121 mark
Which statement about a break-even chart is correct?
AAt the break-even point, sales revenue equals fixed costs.
BIt is a reliable tool for forecasting future performance.
CIt shows costs and revenue over a defined activity range.
DThe sales and variable cost lines intersect at the break-even point.
Show answer
CCorrect answer
Question 29Feb/Mar 20269706/121 mark
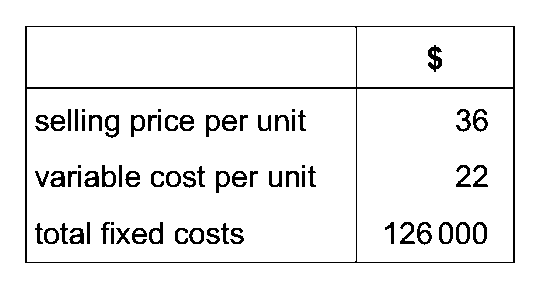
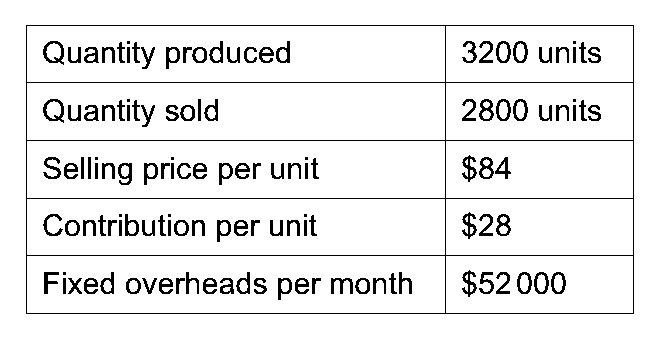
A company produces and sells a single type of product. The following information is available.
What is the sales revenue required to achieve a margin of safety of 40%?
Show answer
DCorrect answer
Question 30Feb/Mar 20269706/121 mark
Why is cost–volume–profit analysis used by management?
Show answer
BCorrect answer
Question 27Oct/Nov 20259706/111 mark
A business adopts marginal costing. How is contribution calculated? A sales revenue less variable production cost less fixed production cost B sales revenue less variable production cost less fixed production cost less variable selling expenses C sales revenue less variable production cost less variable selling expenses D sales revenue less variable production cost less stepped cost
Show answer
CCorrect answer
Question 28Oct/Nov 20259706/111 mark
The following information is available for a manufacturing business.
What is the sales revenue required for the business to make a profit of $200000?
Show answer
DCorrect answer
Question 29Oct/Nov 20259706/111 mark
The following budgeted information relates to June.
There is no opening inventory. What is the budgeted profit in June, using marginal costing?
Show answer
CCorrect answer
Question 30Oct/Nov 20259706/111 mark
What are the major assumptions in cost–volume–profit analysis?
Show answer
BCorrect answer
Question 22Oct/Nov 20259706/121 mark
A business makes a single type of product. The following information is available.
What is the fixed cost per unit?
Show answer
ACorrect answer
Question 27Oct/Nov 20259706/121 mark
What is the correct definition of margin of safety in dollars?
Athe amount by which sales revenue exceeds total fixed and variable costs
Bthe amount by which sales revenue exceeds total marginal costs
Cthe amount by which sales revenue could fall before the break-even point is reached
Dthe total fixed costs divided by contribution per unit sold
Show answer
CCorrect answer
Question 28Oct/Nov 20259706/121 mark
A company had sales revenue of $500000 and total costs of $400000. Fixed costs were $120000. What was the total contribution?
Show answer
BCorrect answer
Question 29Oct/Nov 20259706/121 mark
The following information is available.
What is the break-even point?
Show answer
CCorrect answer
Question 30Oct/Nov 20259706/121 mark
What are the limitations of cost–volume–profit analysis?
Show answer
CCorrect answer
Question 28Oct/Nov 20259706/131 mark
A business has the following budgeted figures for its next financial period.
What is the budgeted total contribution for the period?
Show answer
ACorrect answer
Question 29Oct/Nov 20259706/131 mark
The following information is available for a business.
Fixed costs are expected to increase by $500 per month and variable costs are expected to increase by $5 per unit. Which value of revenue will be required to achieve the target profit?
Show answer
DCorrect answer
Question 30Oct/Nov 20259706/131 mark
Which statements describe assumptions that are made when using cost–volume–profit analysis?
Show answer
BCorrect answer
Question 23May/Jun 20259706/111 mark
A business rents machinery for use in its factory. The rental cost of a machine is $12000. Each machine has the capacity to produce 60000 units. The business provided the following information.
What is the total fixed cost to produce 100000 units?
Show answer
BCorrect answer
Question 24May/Jun 20259706/111 mark
A company sells a product for $12 per batch. The variable cost is $4 per batch. Fixed costs are absorbed based on a normal activity level of 100 batches at $3 per batch. What is the profit under marginal costing if the company makes and sells 125 batches?
Show answer
CCorrect answer
Question 25May/Jun 20259706/111 mark
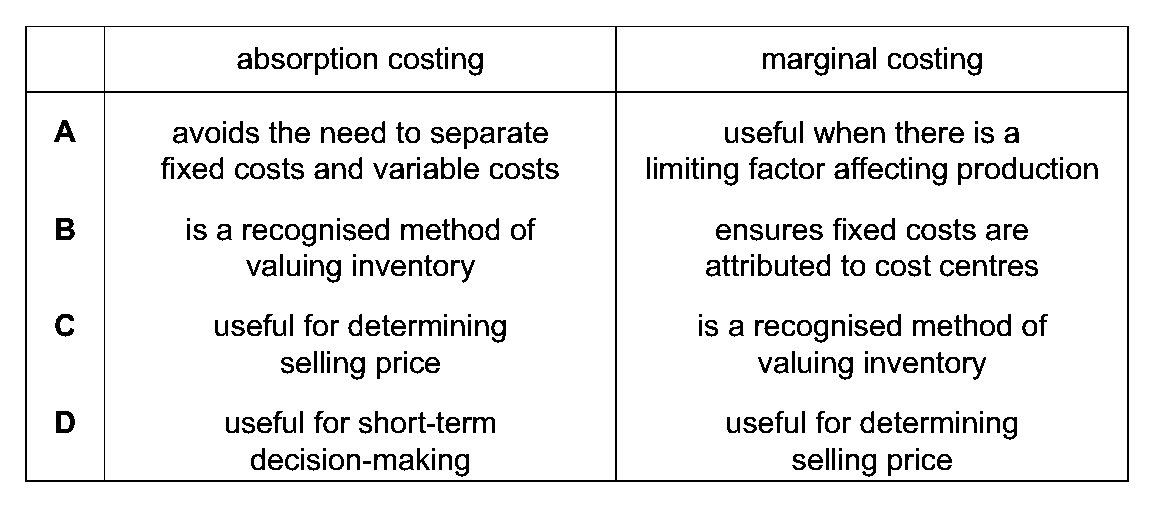
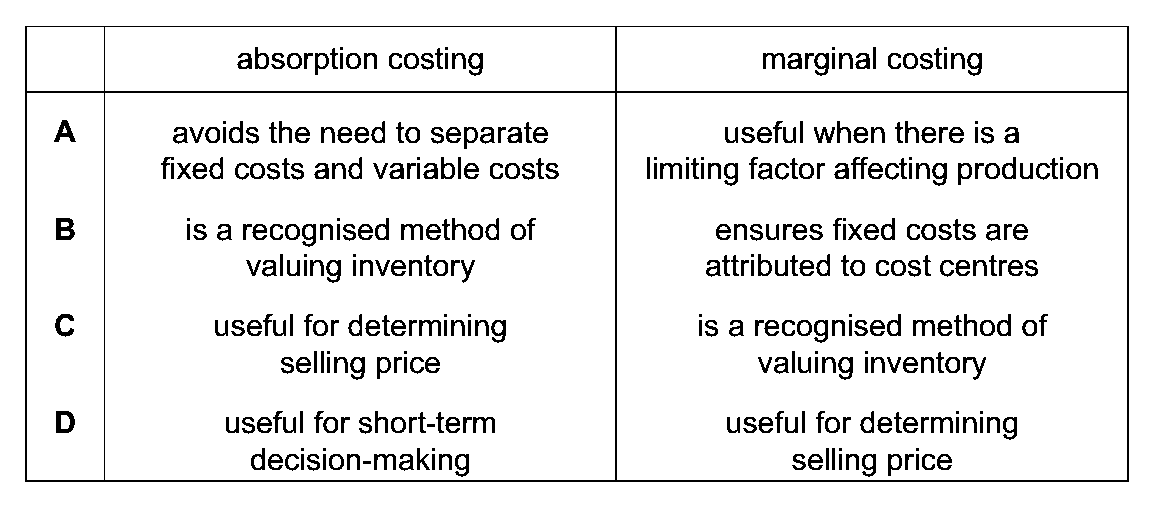
Which statements correctly compare the benefits of absorption and marginal costing?
Show answer
ACorrect answer
Question 27May/Jun 20259706/111 mark
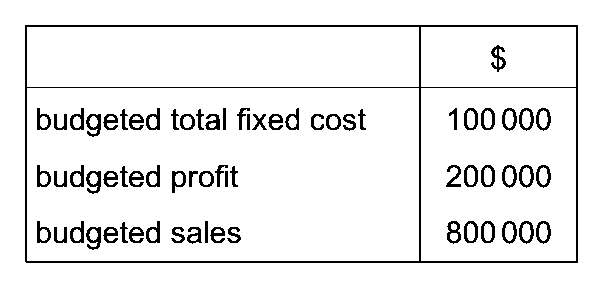
A business has produced the following budget.
What is its budgeted break-even sales revenue?
Show answer
DCorrect answer
Question 28May/Jun 20259706/111 mark
How is a margin of safety calculated?
Aactual total contribution minus break-even contribution
Bactual total contribution minus budgeted total contribution
Cbudgeted total sales units minus actual total sales units
Dbudgeted total sales units minus break-even sales units
Show answer
DCorrect answer
Question 29May/Jun 20259706/111 mark
A business had a contribution to sales ratio of 40%. The following information is available.
It is predicted that the sales revenue will increase by 20% next year. Total fixed costs will remain unchanged. What will be the increase in the profit?
Show answer
ACorrect answer
Question 30May/Jun 20259706/111 mark
The actual output for a business is lower than forecast. Which costs are usually the same as forecast?
Show answer
CCorrect answer
Question 24May/Jun 20259706/121 mark
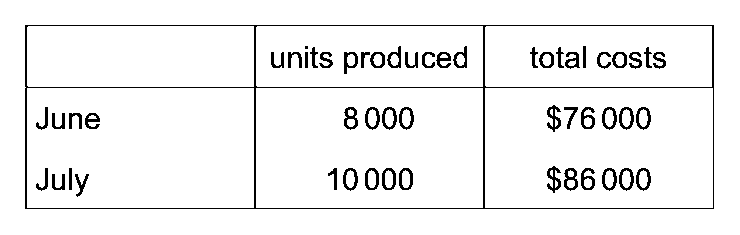
Total costs for each of two months had been recorded. Variable cost per unit remained constant. Total fixed costs increased by $1000 in July.
What was the total of the fixed costs in July?
Show answer
CCorrect answer
Question 28May/Jun 20259706/121 mark
Which factor would cause the variable cost line on a break-even chart not to be a straight line?
Abulk-buying discounts from suppliers
Bemploying an extra factory supervisor
Cplant and machinery depreciation
Drenting additional warehouse space
Show answer
ACorrect answer
Question 29May/Jun 20259706/121 mark
The following information is available for a business.
Fixed costs are expected to increase by $500 per month, and variable costs are expected to increase by $5 per unit. Which value of revenue will be required to achieve the target profit?
Show answer
DCorrect answer
Question 30May/Jun 20259706/121 mark
What are the assumptions of cost−volume−profit analysis?
Show answer
DCorrect answer
Question 23May/Jun 20259706/131 mark
A business rents machinery for use in its factory. The rental cost of a machine is $12000. Each machine has the capacity to produce 60000 units. The business provided the following information.
What is the total fixed cost to produce 100000 units?
Show answer
BCorrect answer
Question 24May/Jun 20259706/131 mark
A company sells a product for $12 per batch. The variable cost is $4 per batch. Fixed costs are absorbed based on a normal activity level of 100 batches at $3 per batch. What is the profit under marginal costing if the company makes and sells 125 batches?
Show answer
CCorrect answer
Question 25May/Jun 20259706/131 mark
Which statements correctly compare the benefits of absorption and marginal costing?
Show answer
ACorrect answer
Question 27May/Jun 20259706/131 mark
A business has produced the following budget.
What is its budgeted break-even sales revenue?
Show answer
DCorrect answer
Question 28May/Jun 20259706/131 mark
How is a margin of safety calculated?
Aactual total contribution minus break-even contribution
Bactual total contribution minus budgeted total contribution
Cbudgeted total sales units minus actual total sales units
Dbudgeted total sales units minus break-even sales units
Show answer
DCorrect answer
Question 29May/Jun 20259706/131 mark
A business had a contribution to sales ratio of 40%. The following information is available.
It is predicted that the sales revenue will increase by 20% next year. Total fixed costs will remain unchanged. What will be the increase in the profit?
Show answer
ACorrect answer
Question 30May/Jun 20259706/131 mark
The actual output for a business is lower than forecast. Which costs are usually the same as forecast?
Show answer
CCorrect answer
Question 27Feb/Mar 20259706/121 mark
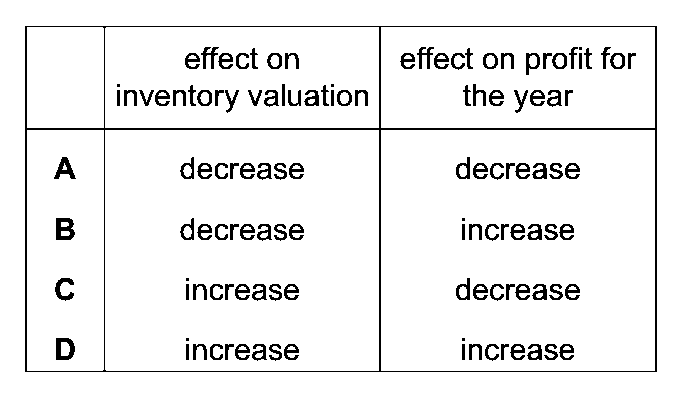
A business prepared its statement of profit or loss for its first year of trading. It used marginal costing to value the inventory. The finance director wants to prepare the statement, using absorption costing. What will be the effect on inventory valuation and profit for the year due to this change?
Show answer
DCorrect answer
Question 28Feb/Mar 20259706/121 mark
The following information was provided about a product.
If the selling price increases, only demand changes. When the selling price increased by $4, profit fell by $1200. What was the decrease in demand?
A214 units
B300 units
C571 units
D657 units
Show answer
BCorrect answer
Question 29Feb/Mar 20259706/121 mark
A manufacturing business provided the following information.
What was the contribution to sales ratio?
Show answer
CCorrect answer
Question 30Feb/Mar 20259706/121 mark
Which assumptions are true about cost–volume–profit analysis?
Show answer
CCorrect answer
Paper 2 · Structured questions (10)
Question 4May/Jun 20269706/2130 marks
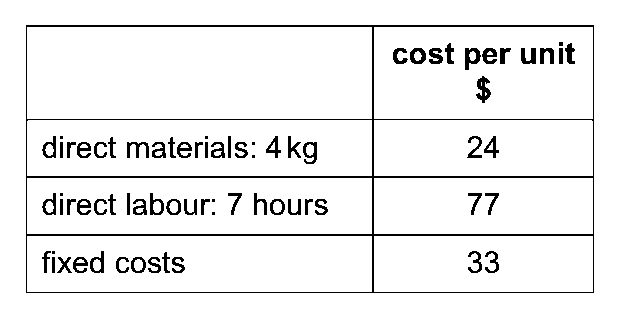
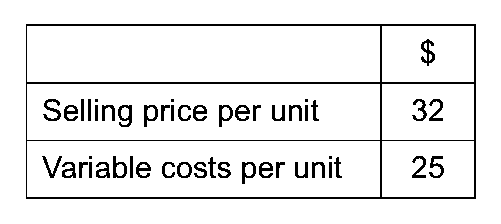
M Limited is a manufacturing company which uses marginal costing at both of its production centres. At one of the factories, a single type of product is made. The following information is available about the product.
The factory capacity is 12 000 units per month. Currently, the factory is working at full capacity, and all units manufactured are sold for $158 per unit.
(a)(i) Calculate each of the following: break-even point in units [3 marks]
(a)(ii) Calculate each of the following: monthly profit. [2 marks]
(b) State three limitations of break-even analysis. [3 marks]
(c) Calculate the change in the break-even point in units per month if the plans are adopted. [4 marks]
The directors are considering making the following changes to improve the quality of the product. 1 Use higher-grade materials which will cost an extra $0.50 per kilogram. The same quantity of materials will be required per unit. 2 Some adjustments will be required to machinery which will increase monthly depreciation charges by $30 000. 3 Direct labour costs will be unaffected. 4 It is expected that production levels and sales levels will remain unchanged.
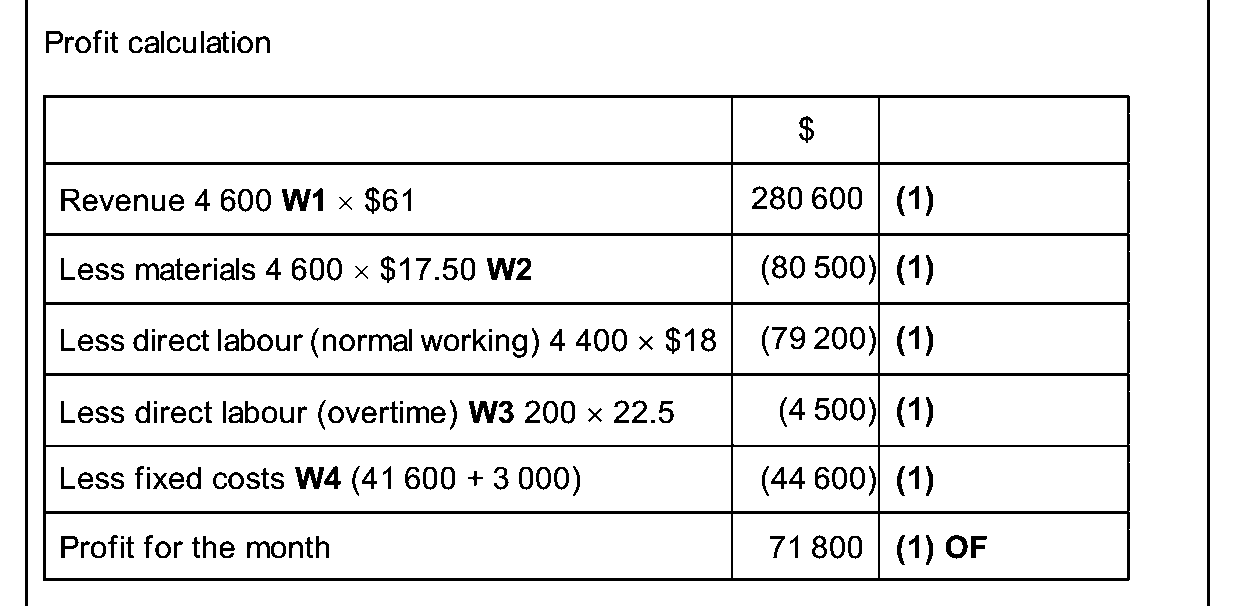
(d) Calculate the budgeted profit or loss for September 2026 if option A is adopted. [8 marks]
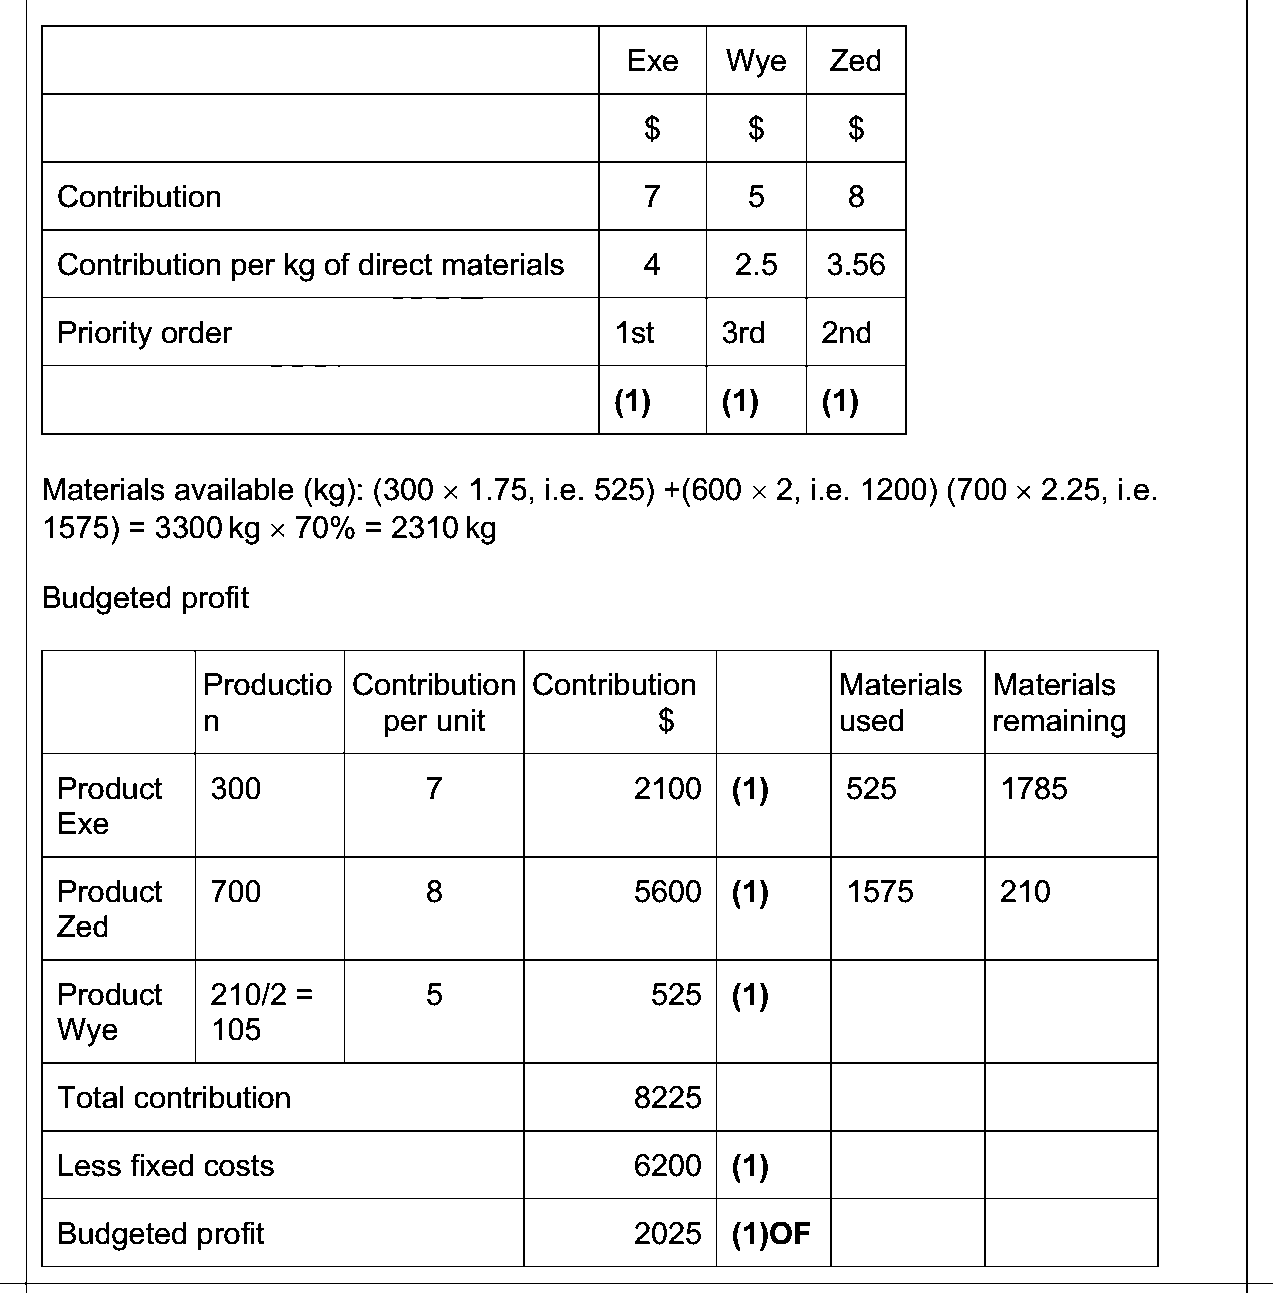
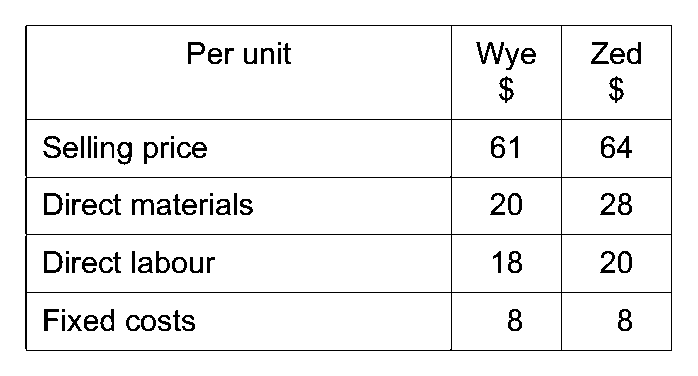
At a second factory, three different products are made: Exe, Wye and Zed. The following information is available:
The same direct materials, which cost $4 per kilogram, are used in making each product. Normally, direct materials are received every two weeks. Fixed costs are budgeted to be $6200 for the month of September 2026. The production capacity for September 2026 is as follows:
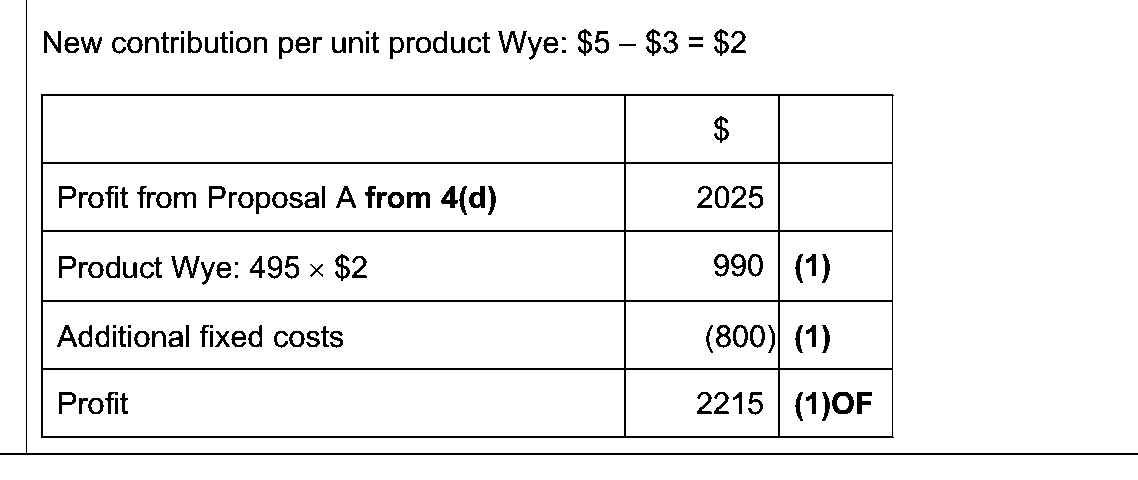
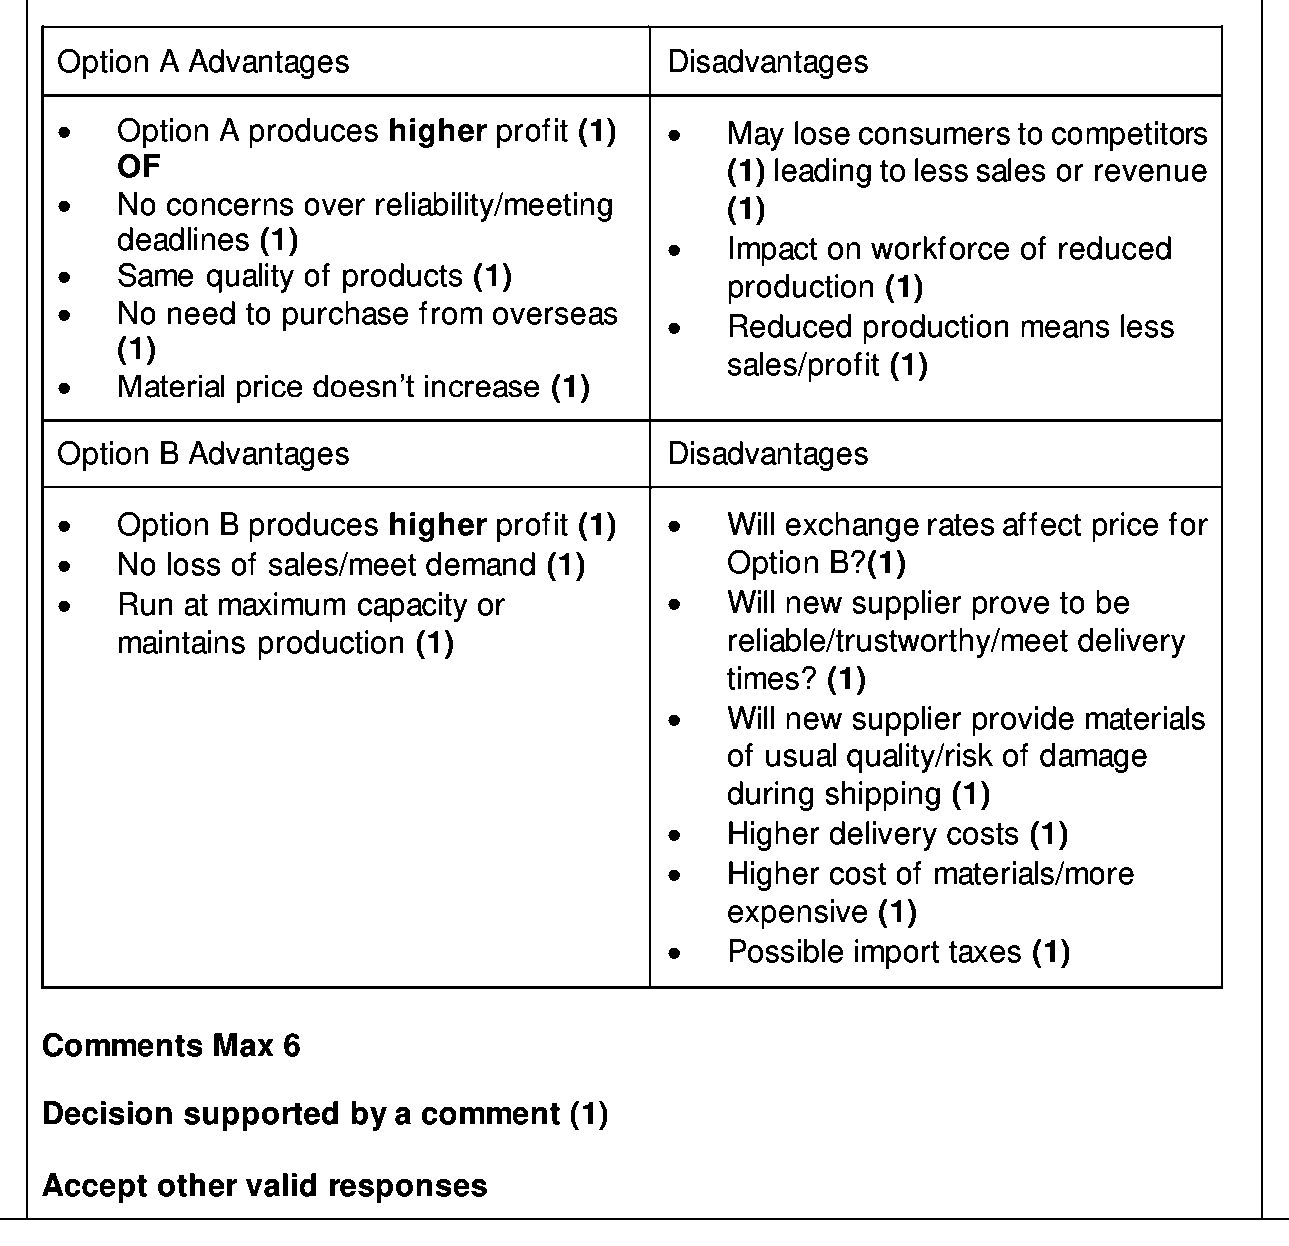
The directors have been informed that the usual supplier can only deliver 70% of the direct materials requirement in September 2026. The directors are planning to implement one of the following options in September 2026. Option A: to change production to achieve the optimum profit for the month. Option B: to order the remaining 30% of direct materials from an alternative supplier who will charge an additional $1.50 per kilogram. In addition, there will be delivery charges amounting to $800, but this supplier can make deliveries at more frequent intervals.
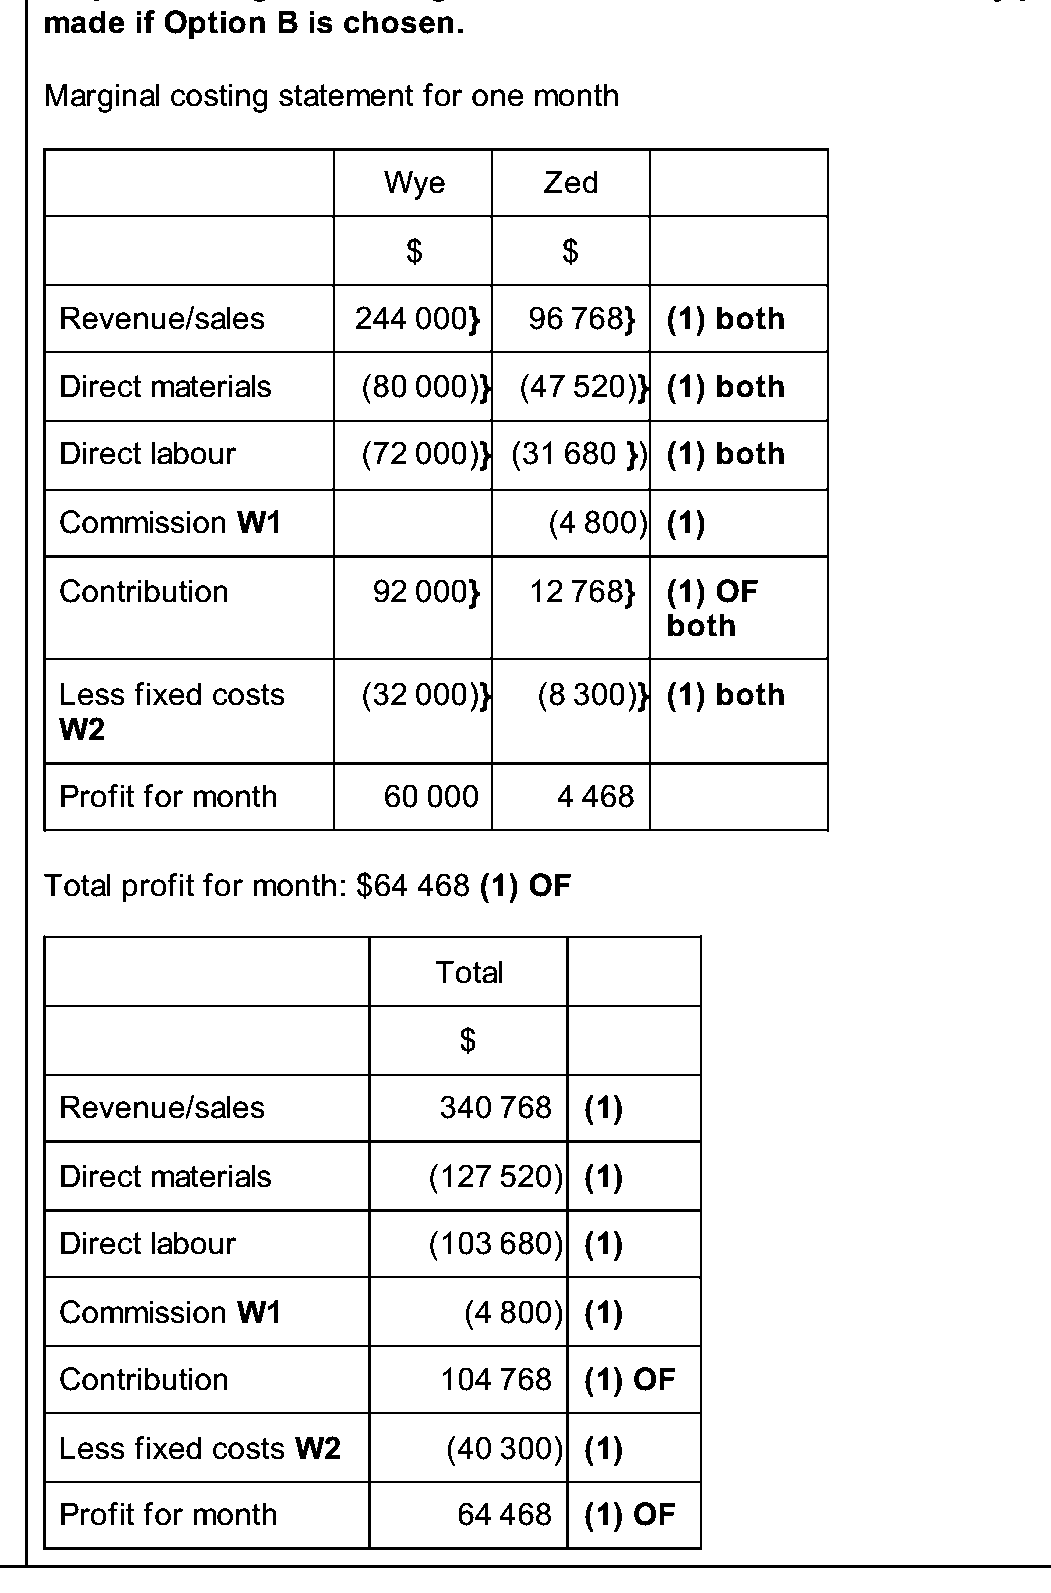
(e) Calculate the budgeted profit or loss for September 2026 if option B is adopted. [3 marks]
(f) Advise the directors which option they should choose. Justify your answer by considering the advantages and disadvantages of each option. [7 marks]
Monthly profit: (12 000 $57, i.e. $684 000) (1) – fixed costs $396 000 = $288 000 (1) Or Monthly profit (12 000 – 6948) units i.e. 5 052 (1) $57 = $287 964 (1)
(b)
fixed costs are assumed to be fixed (1)
assumes all output made is sold (1)
ignores economies of scale such as trade discounts for bulk purchases/assumes variable costs are constant at all levels OR per unit (1)
selling price is assumed to be constant (1)
semi-variable costs are not considered/costs are not easily classified as fixed or variable (1)
there are no changes in the levels of inventory (1)
cannot normally be used if there is a product mix /assumes only one type of product is sold (1) Max 3 Accept other valid responses.
(c)
adopted. Contribution: $57 – increase in materials per unit $2 = $55(1)OF Fixed costs: $396 000 + additional depreciation $30 000 = $426 000 (1) New break-even point: $426 000/55 = 7 746 units (1) Break-even change: 7 746 – 6948 = 798 units increase (1) OF
(d)
(e)
Question 4May/Jun 20269706/2330 marks
M Limited is a manufacturing company which uses marginal costing at both of its production centres. At one of the factories, a single type of product is made. The following information is available about the product.
The factory capacity is 12 000 units per month. Currently, the factory is working at full capacity, and all units manufactured are sold for $158 per unit.
(a)(i) Calculate each of the following: break-even point in units [3 marks]
(a)(ii) Calculate each of the following: monthly profit. [2 marks]
(b) State three limitations of break-even analysis. [3 marks]
(c) Calculate the change in the break-even point in units per month if the plans are adopted. [4 marks]
The directors are considering making the following changes to improve the quality of the product. 1 Use higher-grade materials which will cost an extra $0.50 per kilogram. The same quantity of materials will be required per unit. 2 Some adjustments will be required to machinery which will increase monthly depreciation charges by $30 000. 3 Direct labour costs will be unaffected. 4 It is expected that production levels and sales levels will remain unchanged.
(d) Calculate the budgeted profit or loss for September 2026 if option A is adopted. [8 marks]
At a second factory, three different products are made: Exe, Wye and Zed. The following information is available:
The same direct materials, which cost $4 per kilogram, are used in making each product. Normally, direct materials are received every two weeks. Fixed costs are budgeted to be $6200 for the month of September 2026. The production capacity for September 2026 is as follows:
The directors have been informed that the usual supplier can only deliver 70% of the direct materials requirement in September 2026. The directors are planning to implement one of the following options in September 2026. Option A: to change production to achieve the optimum profit for the month. Option B: to order the remaining 30% of direct materials from an alternative supplier who will charge an additional $1.50 per kilogram. In addition, there will be delivery charges amounting to $800, but this supplier can make deliveries at more frequent intervals.
(e) Calculate the budgeted profit or loss for September 2026 if option B is adopted. [3 marks]
(f) Advise the directors which option they should choose. Justify your answer by considering the advantages and disadvantages of each option. [7 marks]
Monthly profit: (12 000 $57, i.e. $684 000) (1) – fixed costs $396 000 = $288 000 (1) Or Monthly profit (12 000 – 6948) units i.e. 5 052 (1) $57 = $287 964 (1)
(b)
fixed costs are assumed to be fixed (1)
assumes all output made is sold (1)
ignores economies of scale such as trade discounts for bulk purchases/assumes variable costs are constant at all levels OR per unit (1)
selling price is assumed to be constant (1)
semi-variable costs are not considered/costs are not easily classified as fixed or variable (1)
there are no changes in the levels of inventory (1)
cannot normally be used if there is a product mix /assumes only one type of product is sold (1) Max 3 Accept other valid responses.
(c)
adopted. Contribution: $57 – increase in materials per unit $2 = $55(1)OF Fixed costs: $396 000 + additional depreciation $30 000 = $426 000 (1) New break-even point: $426 000/55 = 7 746 units (1) Break-even change: 7 746 – 6948 = 798 units increase (1) OF
(d)
(e)
Question 4Feb/Mar 20269706/2230 marks
V Limited makes one type of product and uses marginal costing.
(a)(i) Define each of the following terms: marginal cost [1 marks]
(a)(ii) Define each of the following terms: stepped costs. [1 marks]
(b) Calculate the current profit per month. [3 marks]
The following information is available about current production.
Units made and sold per month: 3600 Fixed costs per month: $28 260
(c) Calculate the increase in the selling price per unit in order to achieve the target profit. [5 marks]
The directors have made the following decisions:
Increase the labour rate per hour by 5%.
Set a target profit per month of $18 000.
Maintain current levels of production and sales. The directors are aware that they will need to increase the selling price per unit as a result of these decisions.
(d)(i) Prepare marginal costing statements to show the monthly profit to be made for each option. option A [7 marks]
At another factory, which also uses marginal costing, a different product is made. The following forecast information is available.
Units made and sold per month: 8000 Fixed costs per month: $28 700 The factory is currently operating at full capacity. The directors have been informed of a large increase in direct material costs of 50% per unit. They are considering two options. option A
Alter the design of the product so that 20% less materials are required to make one unit.
Increase monthly expenditure on advertising by $4000 as a result of which monthly demand should increase by 10%. The factory can operate in overtime conditions.
In overtime conditions, direct labour is paid a premium of 40%. option B
Order all direct materials from a new supplier.
Maintain current levels of production and sales.
This supplier will also charge the increased cost per unit but is prepared to offer a trade discount of 30% for making bulk orders.
(d)(ii) Prepare marginal costing statements to show the monthly profit to be made for each option. option B [6 marks]
At another factory, which also uses marginal costing, a different product is made. The following forecast information is available.
Units made and sold per month: 8000 Fixed costs per month: $28 700 The factory is currently operating at full capacity. The directors have been informed of a large increase in direct material costs of 50% per unit. They are considering two options. option A
Alter the design of the product so that 20% less materials are required to make one unit.
Increase monthly expenditure on advertising by $4000 as a result of which monthly demand should increase by 10%. The factory can operate in overtime conditions.
In overtime conditions, direct labour is paid a premium of 40%. option B
Order all direct materials from a new supplier.
Maintain current levels of production and sales.
This supplier will also charge the increased cost per unit but is prepared to offer a trade discount of 30% for making bulk orders.
(e) Advise the directors which option they should choose. Justify your choice by discussing both financial and non‑financial factors. [7 marks]
All direct materials are ordered from one supplier. Under option A, the Just in Time (JIT) method of inventory control is used. It is not possible to use JIT for option B.
Show mark scheme
(a)(i)
Marginal cost: the extra cost arising from the production of one more unit (1)
(a)(ii)
Stepped cost: fixed costs which change as different stages of production are reached (1)
profit. Increase in direct labour cost: $2.40 New contribution: $28 260 + 18 000 = $46260 (1) = $12.85 (1)
Either: New selling price: Variable costs $74.40 (1) + new contribution $12.85 = $87.25 (1) Increase in selling price = $3.25 (1) Or: Increase in selling price: $2.40 + $0.85 (1) = $3.25 (1)
(d)(i)
Marginal costing statement for one month
(d)(ii)
Marginal costing statement for one month
Question 4Oct/Nov 20259706/2130 marks
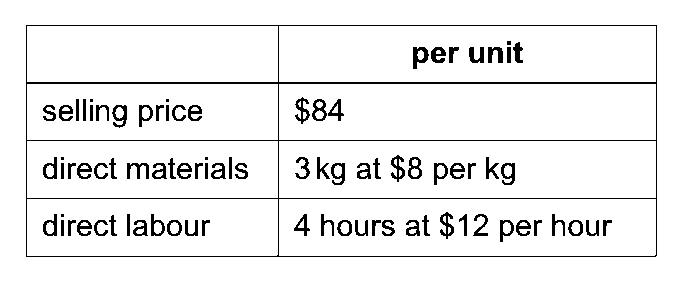
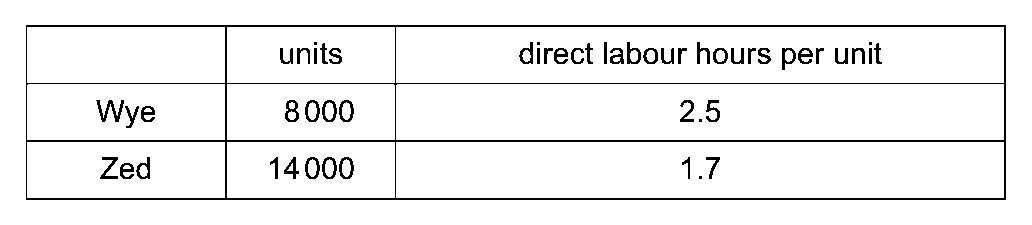
B Limited uses absorption costing at one of its factories where two products are made: Wye and Zed. The budgeted production for January 2026 is as follows:
Budgeted overheads for January 2026 are $67 890.
(a) Calculate, to two decimal places, the overheads to be absorbed by one unit of each product using the direct labour hour method. Wye ........................................................................................................................................... Zed ........................................................................................................................................... [4 marks]
(b) Calculate the total amount of overheads absorbed by each product if budgets are met. Wye ........................................................................................................................................... Zed ............................................................................................................................................ [2 marks]
(c) State two reasons why overheads may be under-absorbed. [2 marks]
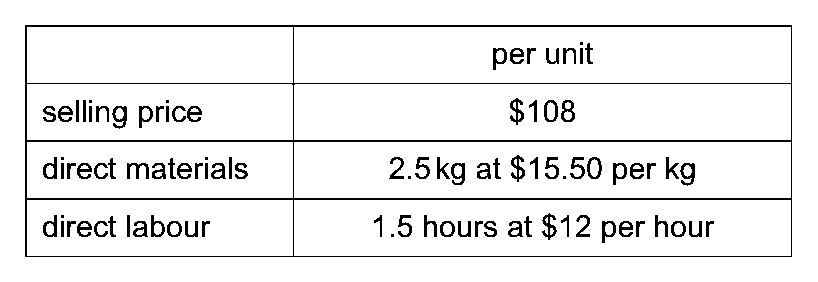
(d) Calculate the total selling price for the order. [5 marks]
The following additional information is available about product Zed.
One unit of product Zed requires direct materials costing $7.
The direct labour rate is $11 per hour.
(e) Calculate the current profit per month. [4 marks]
B Limited manufactures a single type of product at a second factory where marginal costing is used. The following budgeted information is available.
The company relies on one supplier who is currently only able to supply a limited quantity of direct materials. As a result, the factory is producing 14 000 units per month, which is 70% of normal capacity. Currently, the supplier delivers direct materials 4 times each month. Each delivery incurs carriage charges of $4300. Fixed costs per month are forecast to be $136 000 including carriage charges.
(f) Prepare a marginal costing statement for one month if the directors use the overseas supplier. [6 marks]
The directors have contacted an overseas supplier of direct materials.
The materials will cost $20 per kg, which includes carriage charges.
The supplier will make one delivery of direct materials each month. The overseas supplier is prepared to supply sufficient materials for B Limited to work at 90% of normal capacity.
(g) Advise the directors whether or not they should purchase the direct materials from the overseas supplier. Justify your answer by discussing both financial and non-financial factors. [7 marks]
Show mark scheme
(a)
Wye: 2.5 $1.55 = $3.88 per unit (1) Zed: 1.7 $1.55 = $2.64 per unit (1)
(b)
met. Overheads absorbed by: Wye: 8 000 $3.88 = $31 040 (1) OF Zed: 14 000 $2.64 = $36 960 (1) OF Alternative method: Wye: 20000 43800 $67 890 = $31 000 (1) OF Zed: 23800 43800 $67 890 = $36 890 (1) OF
(c)
Actual activity/production level/units produced is less than budgeted activity (1) Actual overheads are greater than budgeted overheads/indirect costs have increased (1)
(d)
(e)
(f)
Question 4Oct/Nov 20259706/2230 marks
W Limited manufactures a single type of product at one of its factories. Currently, marginal costing is used, but the directors have been considering switching to absorption costing.
(a) Identify two features of absorption costing. [2 marks]
(b) Prepare an absorption costing statement to show the profit for September 2024. [6 marks]
The following information is available for September 2024.
There was no inventory on 1 September 2024.
(c) Explain why the profit for marginal costing is different to the profit for absorption costing. [2 marks]
Using marginal costing, the profit for September has been calculated as $26 400.
(d) Calculate the total monthly profit to be made if Option A is chosen. [6 marks]
At a second factory, two different types of products, Wye and Zed, are made, and marginal costing is used. The following budgeted information is available.
The budgeted production and sales for one month are: Wye 4000 units and Zed 1200 units. Demand for Zed has fallen recently and the directors have been considering the following options. Option A 1 Stop production of Zed and increase production and sales of Wye by 15%. 2 All employees will be switched to producing Wye instead of Zed. These employees will need retraining at a cost of $3000. 3 The supplier of materials for Wye will give a larger trade discount as a result of increased orders. Currently the supplier gives a 20% trade discount. This will increase to 30%. 4 It is possible to produce 4400 units of Wye in normal working conditions. Direct labour is paid a premium of 25% for any overtime working. Option B 1 Boost sales of Zed by 20% on current levels by improving its quality. 2 The selling price per unit of Zed will increase by 5%. 3 Direct material cost per unit of Zed will increase to $33 per unit. 4 Direct labour rate per unit of Zed will increase by 10%. 5 The current advertising campaign for Zed, which costs $1300 per month, will be stopped. 6 A sales commission will be paid of $3 per unit for every sale up to the current level of 1200 units per month of Zed, and $5 per unit for every unit over and above 1200 units per month. 7 There is sufficient factory capacity to cover the increased production of Zed.
(e) Prepare a marginal costing statement to show the total monthly profit to be made if Option B is chosen. [7 marks]
(f) Advise the directors which option they should choose. Justify your choice by discussing both financial and non-financial factors. [7 marks]
Show mark scheme
(a)
Charges both variable and fixed costs/all costs (to each unit of production)/no need to separate fixed (and variable) costs (1)
Allocates costs (to cost centres) (1)
Requires apportionment of overheads (which cannot otherwise be allocated to cost centres) (1)
Useful for determining the selling price of a unit (1)
Recognised method for valuing inventory/required for financial statements/acceptable under IAS/IAS 2 or 1 (1)
Helps in long term decision making (1)
Based on the matching principle (1)
Will lead to over or under absorption of overheads (1) Max 2 Accept other valid responses
(b)
(c)
absorption costing. The difference is due to the (valuation of closing) inventory (1) As a result of including fixed overheads/all costs in inventory valuation using absorption costing (1) Marginal costing measure inventory with only variable costs (1) For absorption fixed costs are absorbed into cost of sales (1) With a higher inventory value absorption costing gives a higher profit (1) Max 2 Accept other valid responses
(d)
(e)
Question 4Oct/Nov 20259706/2330 marks
V Limited is a manufacturing company which uses absorption costing at one of its factories.
(a) Explain two differences between marginal costing and absorption costing. [4 marks]
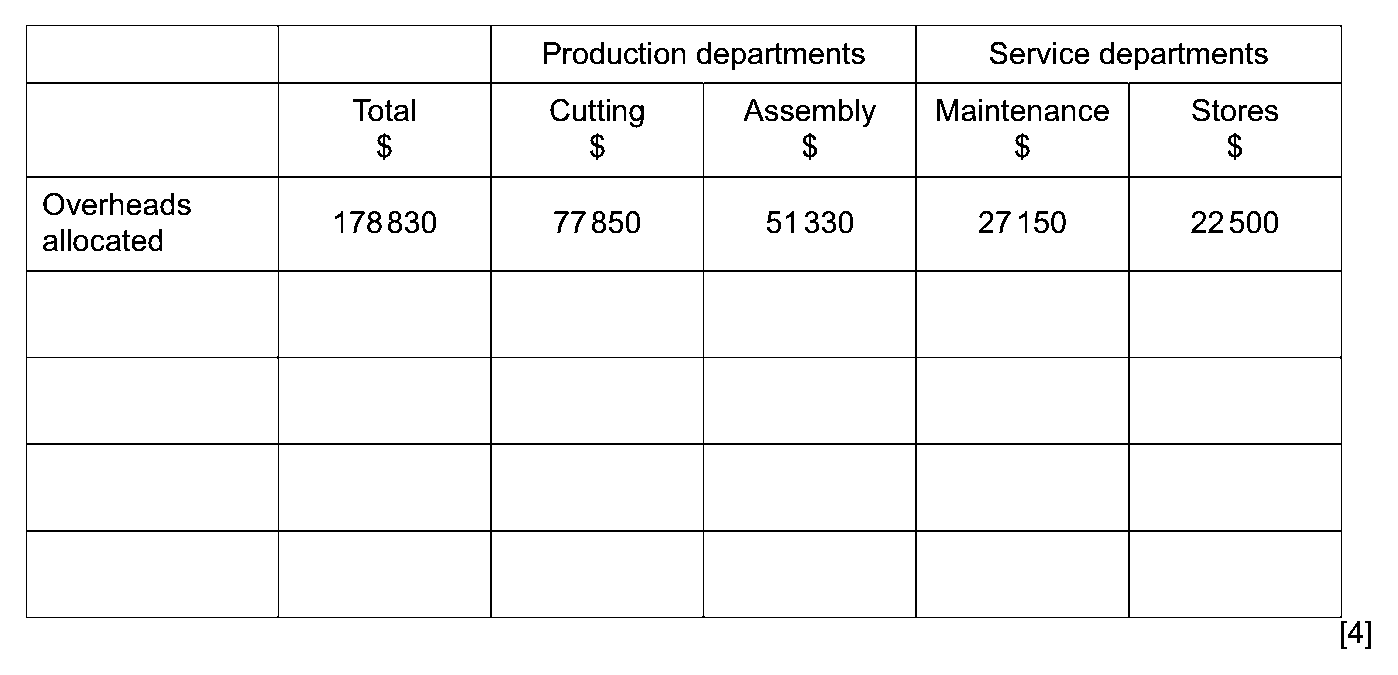
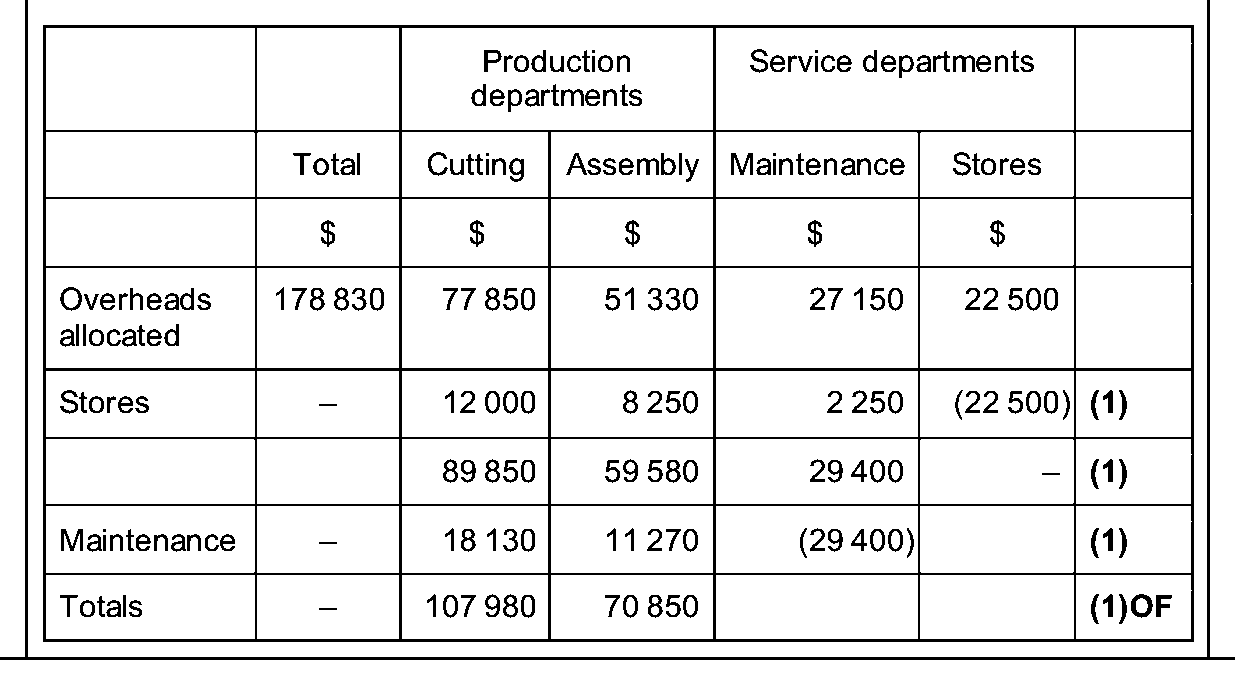
(b) Complete the table to show the reapportionment of service department overheads. [4 marks]
At one of its factories, V Limited has two production departments: cutting and assembly. There are also two service departments: maintenance and stores. All budgeted overheads for the year ended 30 September 2025 have been allocated to departments as follows:
allocated The following additional budgeted information is available about the departments.
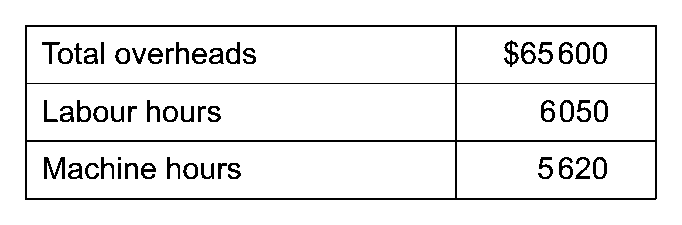
(c) Calculate, to two decimal places, the overhead absorption rates for each department for the year ended 30 September 2025. Cutting department Assembly department [4 marks]
The following forecast information is available for the two production departments for the year ended 30 September 2025.
(d) Calculate the over‑absorption or under‑absorption of overheads for the assembly department for the year ended 30 September 2025. [3 marks]
For the year ended 30 September 2025, actual results for the assembly department were as follows:
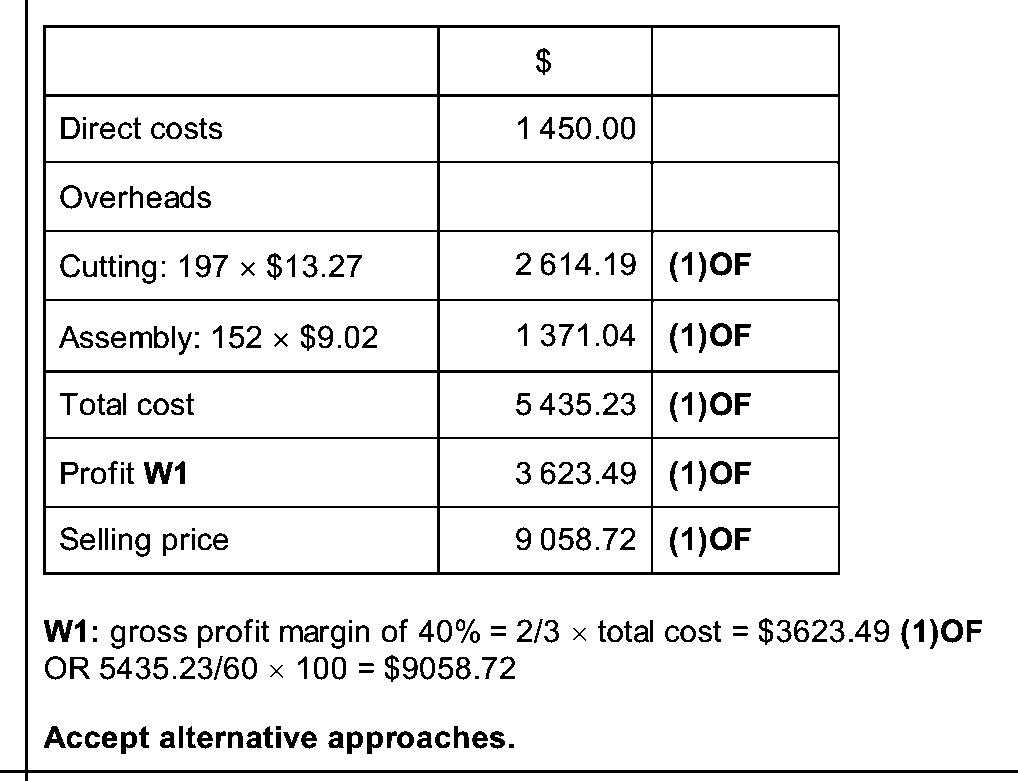
(e) Calculate the selling price of the order. [5 marks]
An order was received from a customer in August 2025. The following information is available.
Products are sold with a gross profit margin of 40%.
(f) Calculate the profit or loss which would be made on the order from the overseas customer. [1 marks]
V Limited uses marginal costing at another factory where a single type of product is made. The following budgeted information is available.
Fixed costs per month are $48 000. Currently, the monthly production and sales are 7200 units which is 60% of normal capacity. However, demand for the product has been falling in recent months. The directors have received an enquiry from an overseas customer who is located in a new market area. 1 The customer would make an order for 1500 units. 2 The customer would pay a reduced price of $29 per unit. 3 V Limited would incur delivery charges of $375 on the order.
(g) Advise the directors whether or not they should accept the order from the overseas customer. Justify your answer by discussing both the advantages and disadvantages of accepting the order. [7 marks]
(h) Explain the key principle of the just in time (JIT) method of inventory control. [2 marks]
Show mark scheme
(a)
Marginal costing treats only variable costs as product cost (1) whereas absorption costing treats both variable and fixed costs as product costs (1) Marginal costing classifies costs by behaviour, as to whether or not they change with the level of output (1) whereas absorption costing classifies costs by nature, whether they are directly or indirectly related to the production process (1) Marginal costing is useful for short term decisions (such as make or buy) (1) whereas absorption costing is useful for long term decisions (such as setting prices) (1) Marginal costing is for internal reporting (1) but absorption is for external reporting/financial statements as it follows IAS (1) Accept other valid responses.
Supplies should be received exactly when they are needed (1) and do not need to be stored by the business beforehand. (1) Accept other valid responses
Question 4May/Jun 20259706/2130 marks
Ameerah’s business uses absorption costing.
(a)(i) Define the following terms: cost centre [1 marks]
(a)(ii) Define the following terms: fixed cost [1 marks]
(a)(iii) Define the following terms: indirect labour. [1 marks]
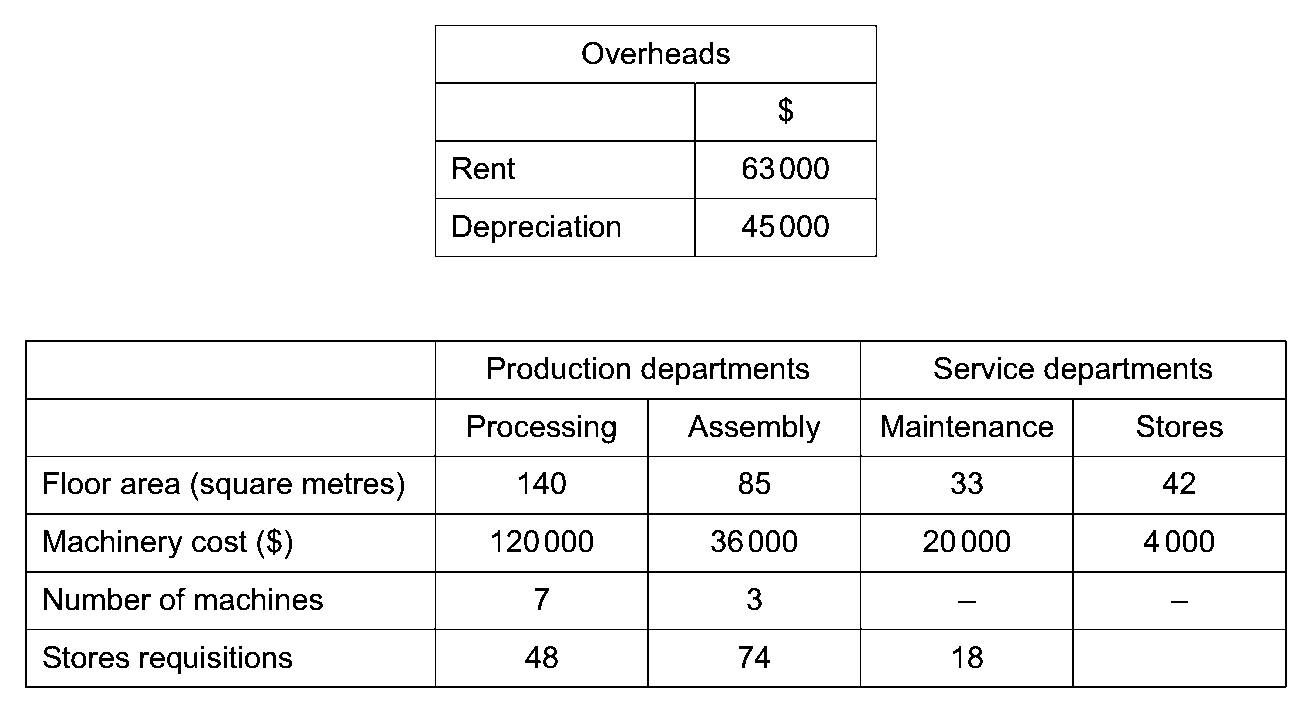
(b) Complete the table to show the total overheads for each department and the reapportionment of service department overheads. [5 marks]
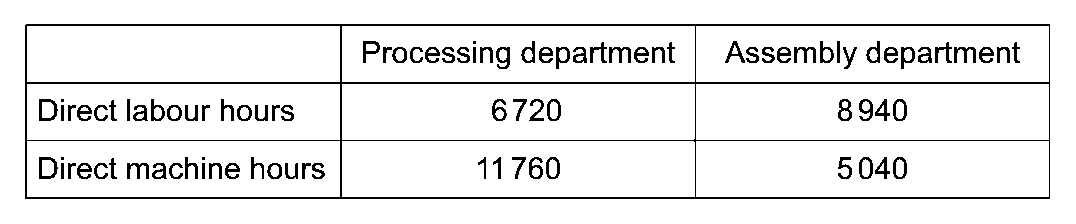
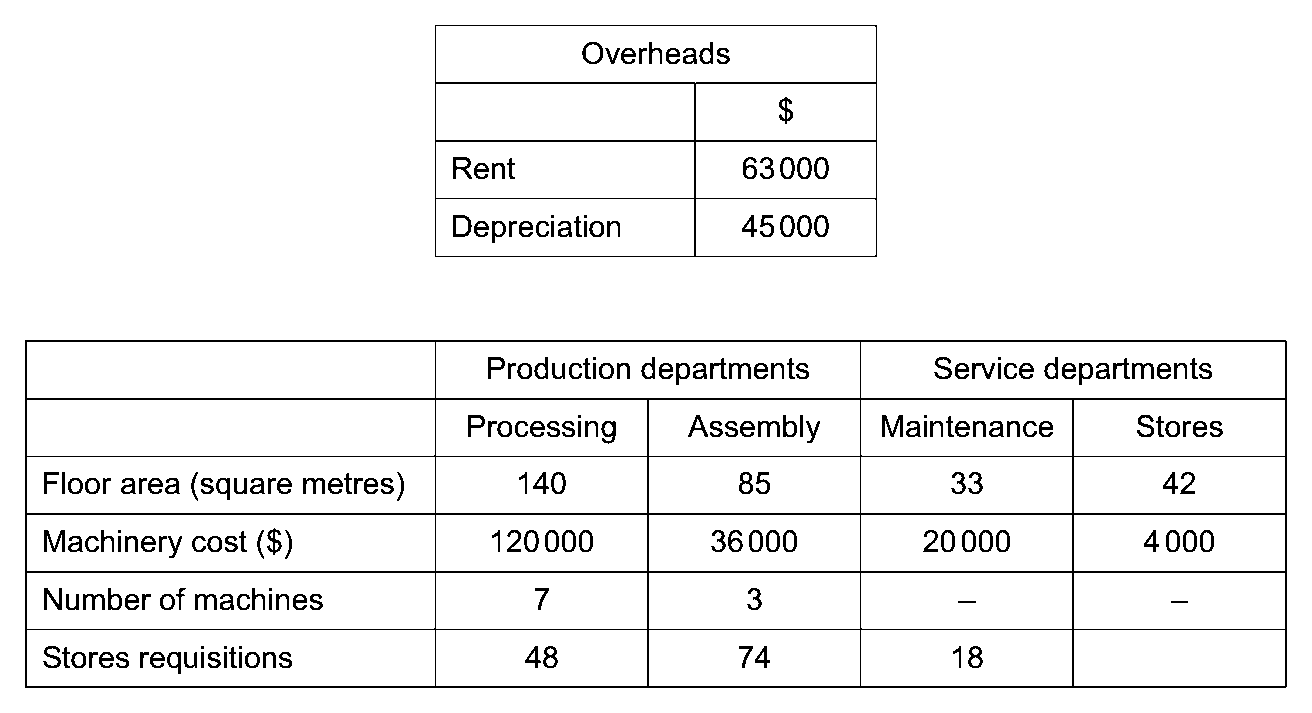
The business operates two production departments: Processing and Assembly, and it operates two service departments: Maintenance and Stores. The following budgeted information is available.
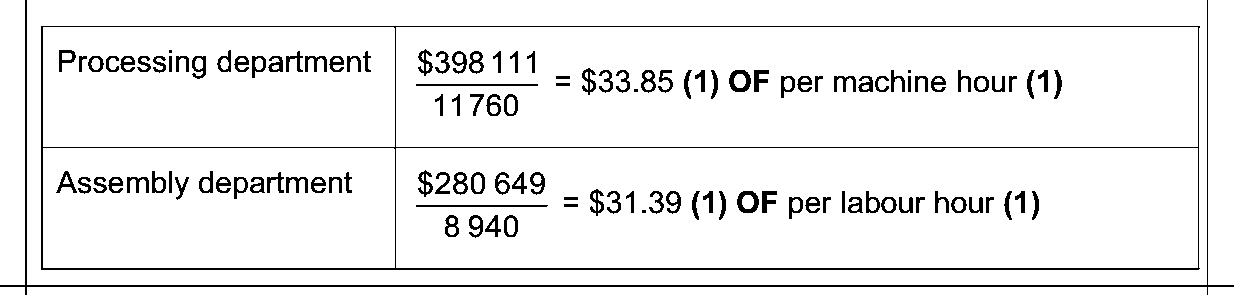
(c) Calculate, to two decimal places, an overhead absorption rate for each production department, using a suitable basis. Processing department Assembly department [4 marks]
Budgeted hours for each production department were as follows:
(d) State two reasons why overheads may be under-absorbed. [2 marks]
(e) Calculate the amount saved per unit by paying experienced labour at a higher rate. [3 marks]
The following information is available about pay rates for direct labour in the Processing department.
Normally direct labour is paid $9.60 per hour for a 32-hour week. Normal output is 24 units per hour.
Sometimes more experienced direct labour is available and is paid $10.50 per hour for a 30-hour week. Normal output is 30 units per hour.
The company expects to make a gain on the cost of labour per unit by paying a higher rate to more experienced employees.
(f) Prepare a statement to show the total selling price for the customer’s order. [8 marks]
A customer has made an order for 300 units of a product. Each unit will require the following:
Direct labour rate will be as follows:
Selling prices are set to achieve a profit margin of 60%.
(g) Advise Ameerah whether or not she should use marginal costing rather than absorption costing. Justify your advice. [5 marks]
Ameerah is concerned that she may be losing customers due to high selling prices. She has been considering using marginal costing rather than absorption costing in order to enable more competitive pricing.
Show mark scheme
(a)(i)
cost centre a department/service location/activity to which costs can be attributed (1)
(a)(ii)
fixed cost A cost that remains unchanged within a certain level of activity / output (1)
(a)(iii)
indirect labour costs of employees whose work cannot be directly identified with the finished product (1)
(b)
(c)
(d)
Under absorption of overheads occurs when either actual expenditure is more than budgeted expenditure (1) and/or production is less than planned (1).
(e)
rate. Lower rate: $9.60 per hour / 24 units = $0.40 per unit (1) Higher rate: $10.50 per hour/30 units = $0.35 per unit (1) The amount saved is $0.05 per unit (1) OF
(f)
W1 Profit = 1.5 cost $50 235.75 OR
(g)
For the change (max 2) Marginal costing will enable prices to be set more flexibly (1) enabling the business to be more competitive Will be useful for other short-term decision making situations (such as limiting factor decisions as well as special order pricing) (1) Avoids some problems associated with absorption costing (such as arbitrary apportionment of overheads) (1) Against the change (max 2) Risk that fixed costs may not be covered (1) May be difficulties in establishing the marginal cost where some costs have both fixed and variable elements (1) Ignores the fact that in the long run all costs are variable (1) Max 4 Accept other valid responses Decision supported with a comment (1)
Question 4May/Jun 20259706/2230 marks
M Limited manufactures a single product at one of its factories. The company uses marginal costing.
(a)(i) Define the following terms: contribution [1 marks]
(a)(ii) Define the following terms: fixed costs [1 marks]
(a)(iii) Define the following terms: margin of safety. [1 marks]
(b)(i) Calculate the following in units: break-even point [3 marks]
Currently, the factory is operating at full capacity of 8300 units per month. All production is sold. The following details are available about the single product.
The directors have a target profit of $35 000 per month.
(b)(ii) Calculate the following in units: margin of safety. [1 marks]
Currently, the factory is operating at full capacity of 8300 units per month. All production is sold. The following details are available about the single product.
The directors have a target profit of $35 000 per month.
(c) Calculate the amount by which the monthly target profit is exceeded. [2 marks]
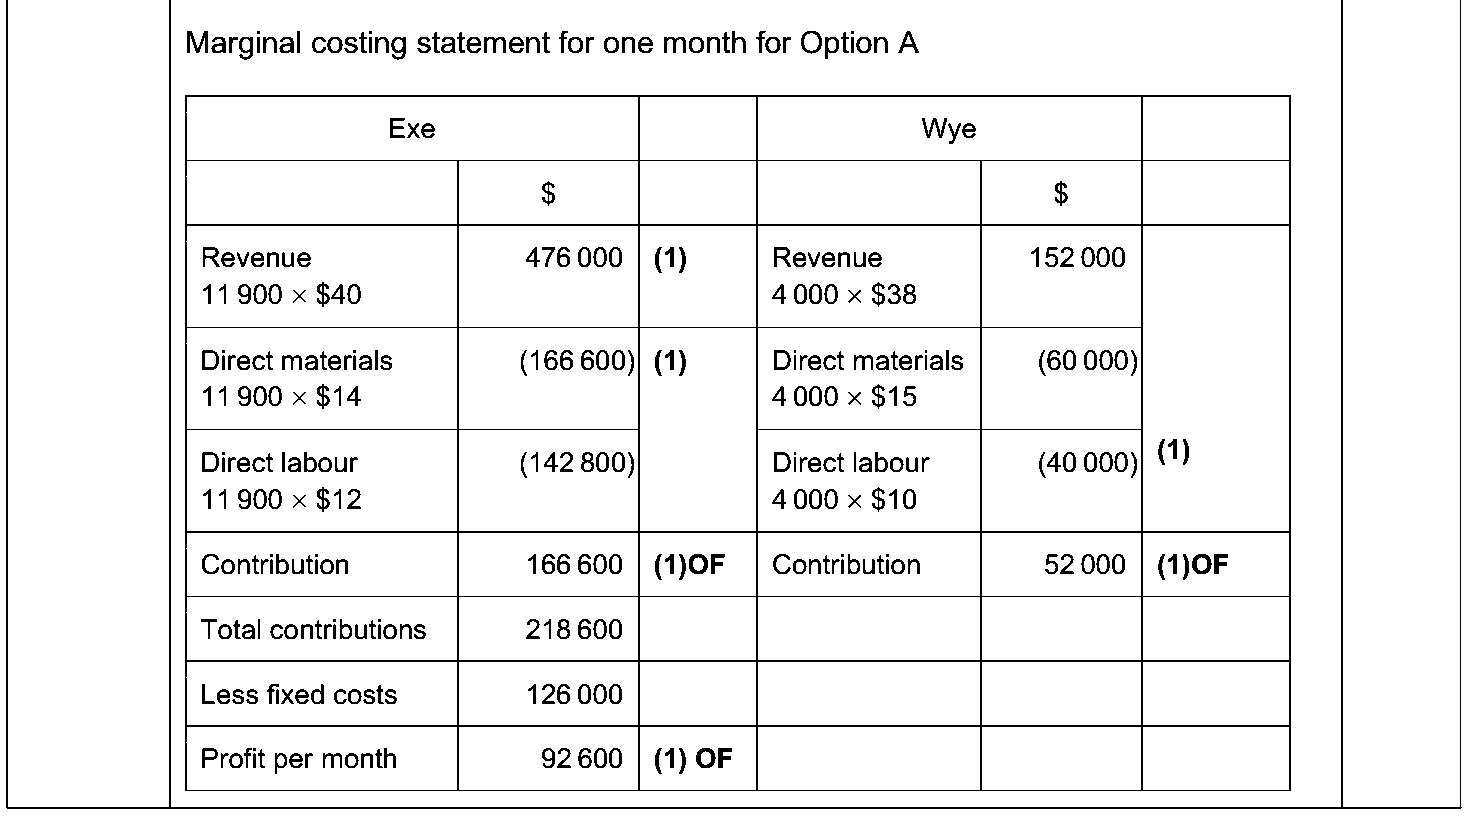
(d) Prepare a marginal costing statement for Option A to show the total monthly profit being made. [6 marks]
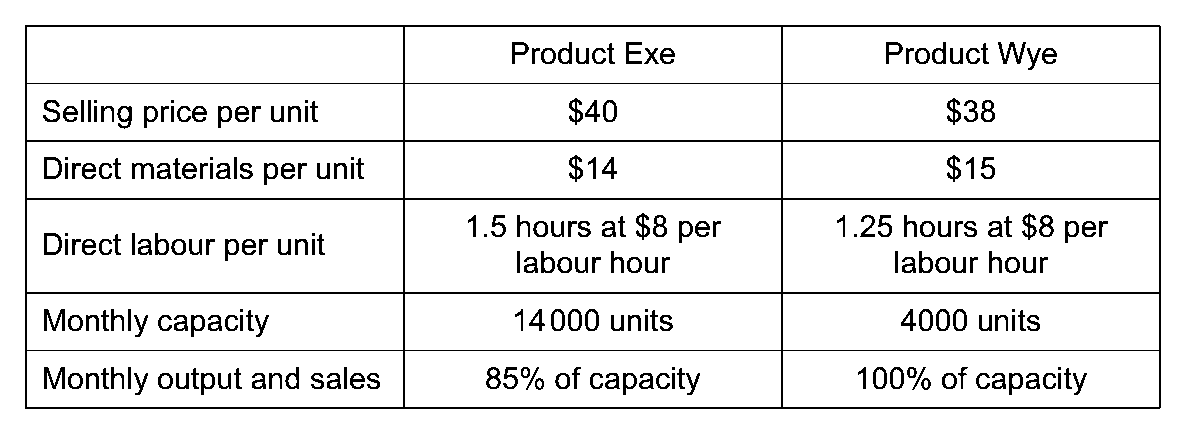
At a second factory, two products are currently being made, Product Exe and Product Wye. The following budgeted information is available.
The factory’s fixed costs per month are $126 000. The directors are aware that an overseas supplier could provide Product Wye resulting in a contribution to M Limited of $17 per unit. The overseas supplier can supply 3000 units per month. The directors are considering two options. Option A Continue with the production and sales of both Products Exe and Wye as now. Option B 1 Stop production of Product Wye, and buy in 3000 units from the overseas supplier. 2 Most direct labour currently making Product Wye would be used to make additional units of Product Exe so that output reaches full capacity. 3 To sell all output of Product Exe, the selling price of all units of Product Exe would be reduced by 2.5%. 4 The directors will negotiate an increase in trade discount from 20% to 25% on all purchases of direct materials for Product Exe. 5 Direct labour currently producing Product Wye would require retraining at a cost of $5000 to be written off at the start of the first month of operation. 6 The machinery currently used for production of Product Wye has a carrying value of $23 000 and would be written off at the start of the first month of operation.
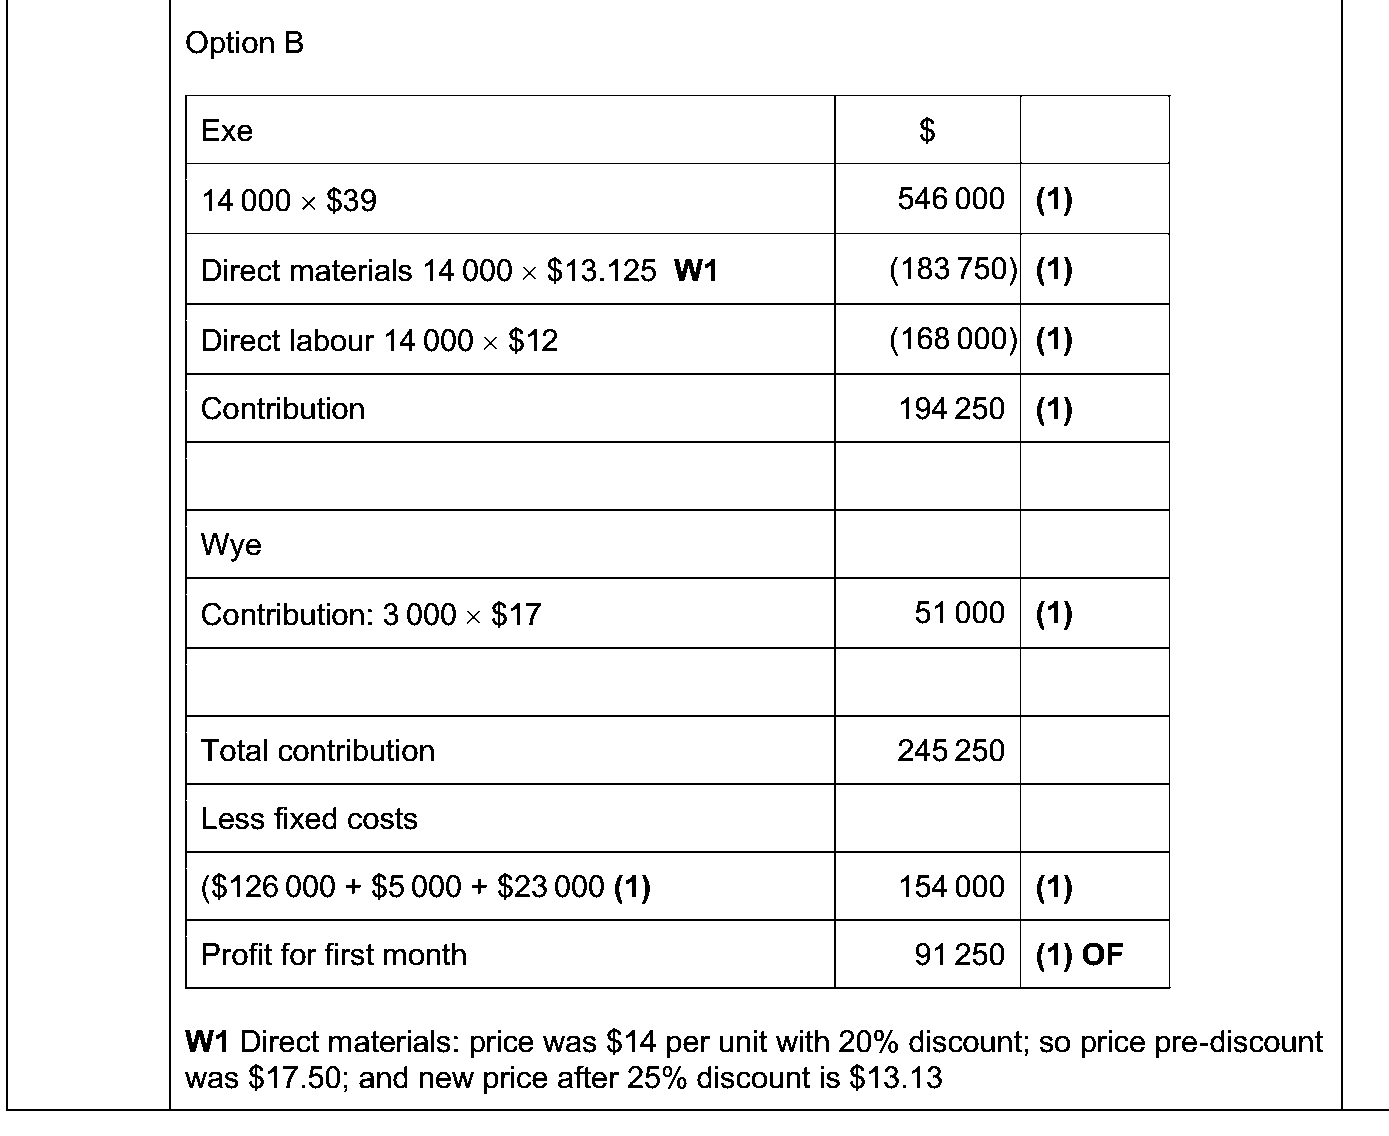
(e) Calculate the total profit to be made in the first month of operation if Option B is adopted. [8 marks]
(f) Advise the directors which option they should choose. Justify your choice by discussing both financial and non-financial factors for each option. [7 marks]
Show mark scheme
(a)(i)
contribution Contribution is the difference between selling price and variable costs (1)
(a)(ii)
fixed costs Fixed costs are costs which do not change with levels of business activity (1)
(a)(iii)
margin of safety Margin of safety is the difference between sales and break-even level of sales (1)
(b)(i)
break-even point Contribution $11 (1); Fixed costs 6 8 300 = $49 800 (1) Break-even point 4 528 units (1)
(b)(ii)
margin of safety 8 300 – 4 528 = 3 772 units (1) OF
profit being made. Marginal costing statement for one month for Option A
(e)
is adopted. Option B
Question 4May/Jun 20259706/2330 marks
Ameerah’s business uses absorption costing.
(a)(i) Define the following terms: cost centre [1 marks]
(a)(ii) Define the following terms: fixed cost [1 marks]
(a)(iii) Define the following terms: indirect labour. [1 marks]
(b) Complete the table to show the total overheads for each department and the reapportionment of service department overheads. [5 marks]
The business operates two production departments: Processing and Assembly, and it operates two service departments: Maintenance and Stores. The following budgeted information is available.
(c) Calculate, to two decimal places, an overhead absorption rate for each production department, using a suitable basis. Processing department Assembly department [4 marks]
Budgeted hours for each production department were as follows:
(d) State two reasons why overheads may be under-absorbed. [2 marks]
(e) Calculate the amount saved per unit by paying experienced labour at a higher rate. [3 marks]
The following information is available about pay rates for direct labour in the Processing department.
Normally direct labour is paid $9.60 per hour for a 32-hour week. Normal output is 24 units per hour.
Sometimes more experienced direct labour is available and is paid $10.50 per hour for a 30-hour week. Normal output is 30 units per hour.
The company expects to make a gain on the cost of labour per unit by paying a higher rate to more experienced employees.
(f) Prepare a statement to show the total selling price for the customer’s order. [8 marks]
A customer has made an order for 300 units of a product. Each unit will require the following:
Direct labour rate will be as follows:
Selling prices are set to achieve a profit margin of 60%.
(g) Advise Ameerah whether or not she should use marginal costing rather than absorption costing. Justify your advice. [5 marks]
Ameerah is concerned that she may be losing customers due to high selling prices. She has been considering using marginal costing rather than absorption costing in order to enable more competitive pricing.
Show mark scheme
(a)(i)
cost centre a department/service location/activity to which costs can be attributed (1)
(a)(ii)
fixed cost A cost that remains unchanged within a certain level of activity / output (1)
(a)(iii)
indirect labour costs of employees whose work cannot be directly identified with the finished product (1)
(b)
(c)
(d)
Under absorption of overheads occurs when either actual expenditure is more than budgeted expenditure (1) and/or production is less than planned (1).
(e)
rate. Lower rate: $9.60 per hour / 24 units = $0.40 per unit (1) Higher rate: $10.50 per hour/30 units = $0.35 per unit (1) The amount saved is $0.05 per unit (1) OF
(f)
W1 Profit = 1.5 cost $50 235.75 OR
(g)
For the change (max 2) Marginal costing will enable prices to be set more flexibly (1) enabling the business to be more competitive Will be useful for other short-term decision making situations (such as limiting factor decisions as well as special order pricing) (1) Avoids some problems associated with absorption costing (such as arbitrary apportionment of overheads) (1) Against the change (max 2) Risk that fixed costs may not be covered (1) May be difficulties in establishing the marginal cost where some costs have both fixed and variable elements (1) Ignores the fact that in the long run all costs are variable (1) Max 4 Accept other valid responses Decision supported with a comment (1)
Question 4Feb/Mar 20259706/2230 marks
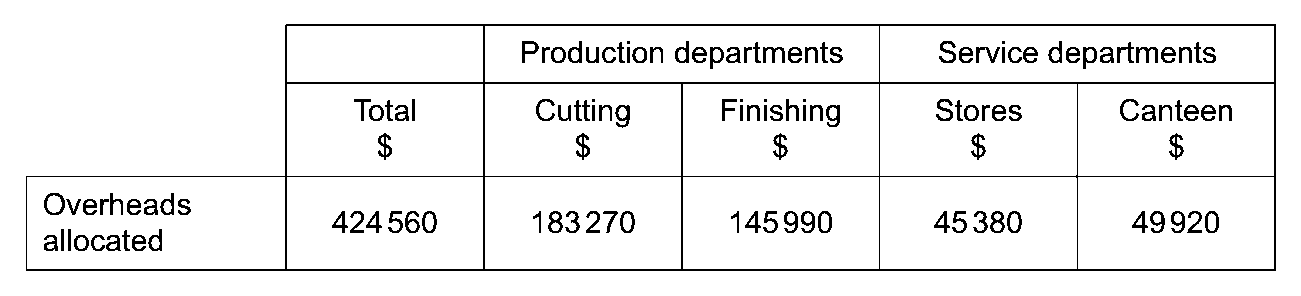
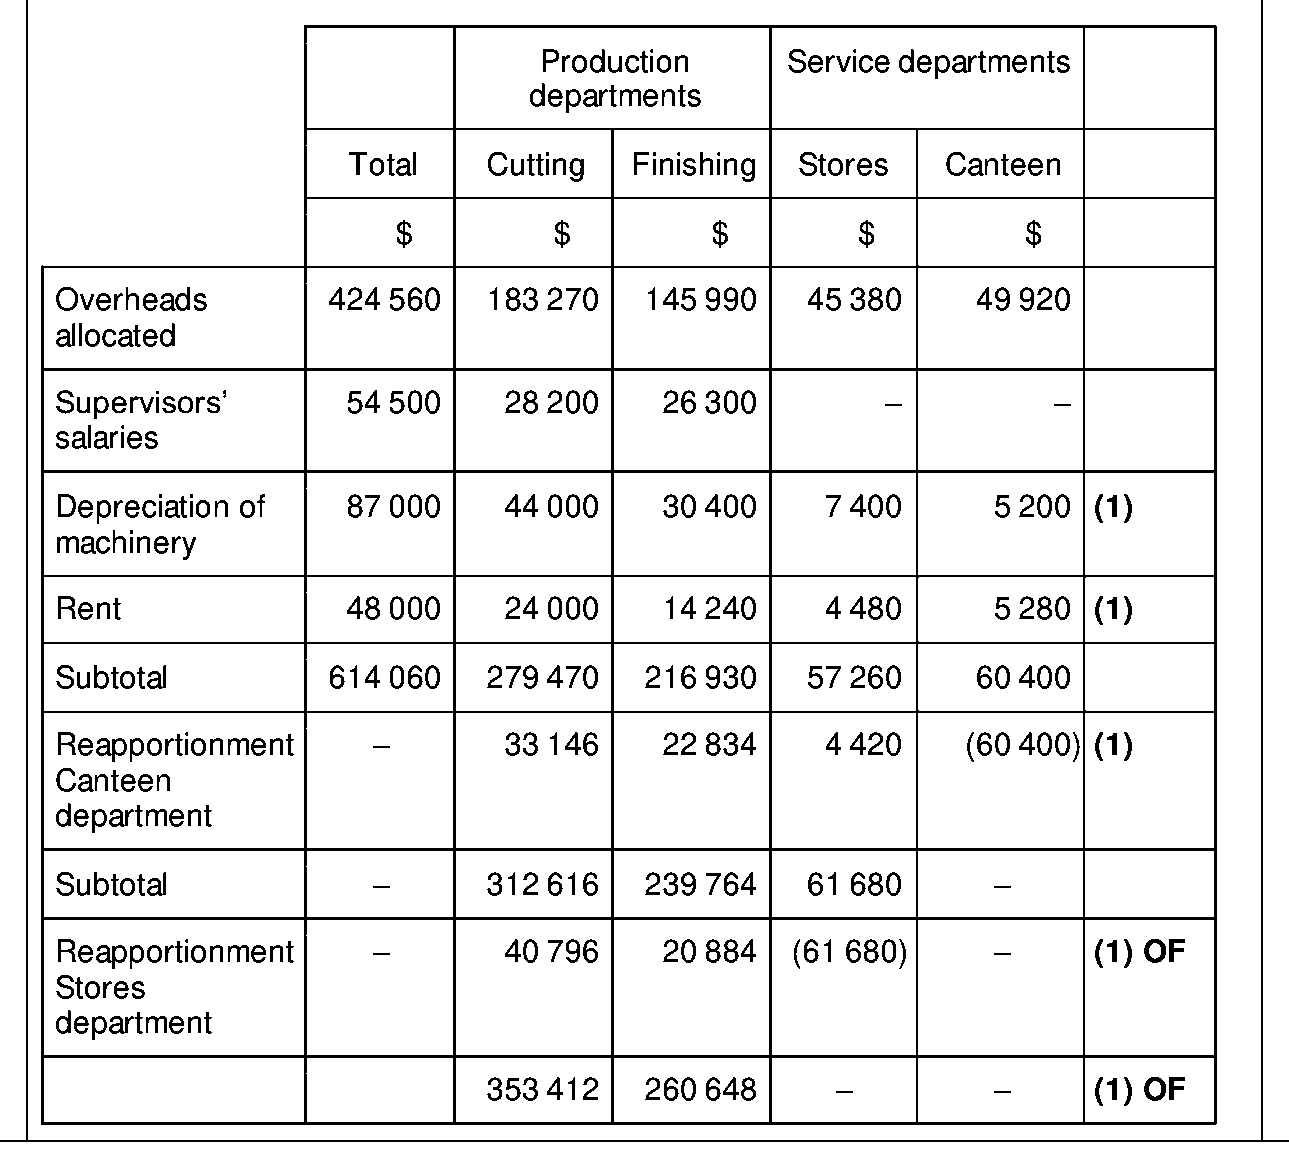
D Limited is a manufacturing company which uses absorption costing. The factory has two production departments, Cutting and Finishing. It also has two service departments, Stores and Canteen. Some budgeted overheads have been allocated to departments as follows:
allocated The following budgeted overheads have yet to be allocated or apportioned.
Apportionment is based on the following information.
(a) Complete the following table to show the apportionment of overheads and the reapportionment of service department overheads. [5 marks]
(b) Calculate, to two decimal places, an overhead absorption rate for each production department, using a suitable basis. Cutting department Finishing department [4 marks]
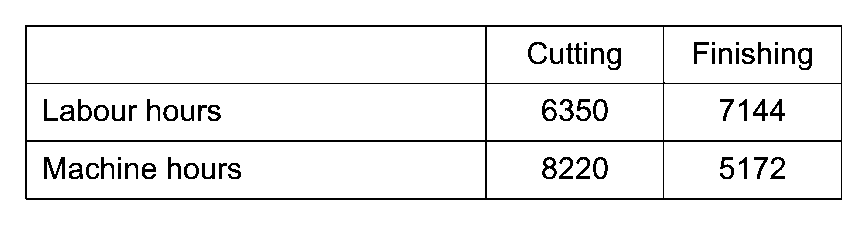
Budgeted hours for each production department were as follows:
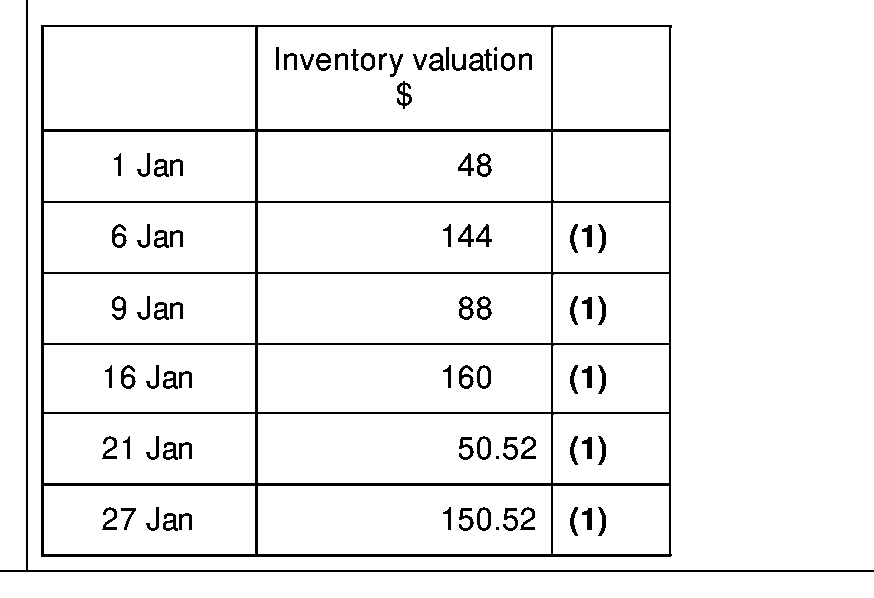
(c) Complete the following table to show the value of the closing inventory of component X, using AVCO. [5 marks]
The Stores department issues component X to the Finishing department. The weighted average cost (AVCO) method of inventory control is used by the Stores department. The following details about this component are available for January 2025. On 1 January 2025, the Stores department held six component X in inventory which had cost $8 each.
Workings:
(d)(i) Calculate the profit to be made in August 2025 for each option. Option A [6 marks]
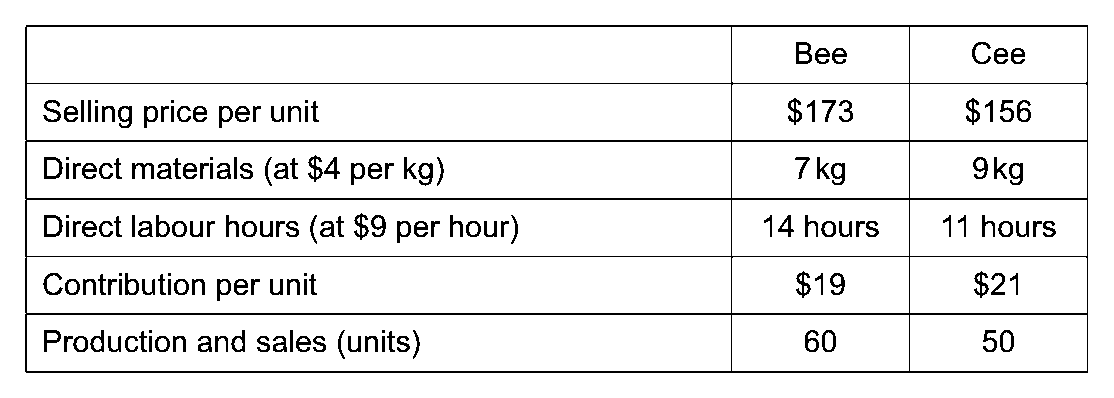
D Limited uses marginal costing at another factory where two products, Bee and Cee, are made. The following forecast information is available for August 2025.
Fixed costs are $1100 per month. The supplier of direct materials has notified the directors that delivery problems will mean that in August 2025 only 70% of the forecast requirement for direct materials will be available. The directors are considering two options for August 2025. Option A: Organise production in order to produce the maximum profit with the available materials. Option B: Purchase additional materials from a new overseas supplier to make up the shortfall. The supplier charges $5 per kg.
(d)(ii) Calculate the profit to be made in August 2025 for each option. Option B [3 marks]
D Limited uses marginal costing at another factory where two products, Bee and Cee, are made. The following forecast information is available for August 2025.
Fixed costs are $1100 per month. The supplier of direct materials has notified the directors that delivery problems will mean that in August 2025 only 70% of the forecast requirement for direct materials will be available. The directors are considering two options for August 2025. Option A: Organise production in order to produce the maximum profit with the available materials. Option B: Purchase additional materials from a new overseas supplier to make up the shortfall. The supplier charges $5 per kg.
(e) Advise the directors which option they should choose. Justify your answer. [7 marks]
Show mark scheme
(a)
(c)
(d)(i)
(d)(ii)
Option B Remaining units of Cee (50-21) = 29 units (1) New contribution Cee: $21 – $9 = $12 (1) Profit: as for option A $481 + (29 $12) = $829 (1)
(e)
134 more questions from 2020–2024
🔒 Unlock every Marginal costing question from 2020–2024
All 134 come with their mark schemes, answers and case studies, and appear in the practice tool above once you’re signed in. It’s free.
9706/11 · Oct/Nov 2024 · Question 27The canteen costs of a business have… 🔒
9706/11 · Oct/Nov 2024 · Question 28What is a limitation of… 🔒
+ 129 more, by year in the table above
Questions and mark schemes are from past Cambridge papers and are reproduced for revision. Topical Vault is an independent revision resource, not affiliated with or endorsed by Cambridge Assessment International Education.
AS Level Accounting questions by topic
Each topic opens this practice tool with only that topic’s questions, plus how often it comes up and every question on it in one list.
Pick a paper, sub-topics and years to draw from (leave any blank for "all"), choose
how many questions you want, and we'll open a new worksheet page with a random set for you to review
and download.